Lost Earning Capacity vs Lost Wages
Getting into a car accident is never just about the immediate crash; it often sends ripple effects through every aspect of your life, especially your finances. One of the most common and distressing impacts is the inability to work and earn a living, whether it's for a short time or, tragically, for years to come. This guide aims to clear up the confusion between two critical concepts in a car accident claim: lost wages and lost earning capacity, helping you understand how these financial losses are calculated and claimed so you can pursue the compensation you deserve.
Understanding the Immediate Financial Blow: Lost Wages
When a car accident leaves you injured, one of the first things you likely think about, after your health, is how you're going to pay the bills without your regular income. This immediate financial hit is what we commonly refer to as lost wages. It's the most straightforward part of your economic damages claim, but that doesn't mean it's always easy to prove, especially if your work situation isn't a simple salary.
What Exactly Are Lost Wages?
Lost wages, at their core, represent the income you would have earned had the accident not occurred and prevented you from working. This isn't just your base salary; it's a comprehensive look at all the money you've missed out on directly due to your injuries. Think of it as the paycheck that never showed up because you were in a hospital bed, at physical therapy, or simply too incapacitated to perform your job duties.
This category typically includes your regular hourly pay, salary, overtime hours you reliably worked, bonuses, commissions, tips, and even certain employer-provided benefits that have a monetary value, like paid time off or contributions to a retirement account, if you lost them. For someone working a steady 9-to-5 job with a fixed salary, calculating this might seem simple, a matter of multiplying your daily rate by the number of days missed. But for others, like freelancers, gig workers, or those with highly variable income, it can get a lot more intricate. The key is to prove a direct, undeniable link between your accident injuries and your inability to earn that specific income during a defined period.
How to Calculate Lost Wages After an Accident
Calculating lost wages requires diligent record-keeping and a clear understanding of your pre-accident earnings. It's not enough to just say, "I missed a month of work." You need to provide concrete evidence that shows what you would have earned. The process usually involves several steps, starting with gathering all relevant financial documents.
First, collect recent pay stubs, W2 forms, 1099 forms (for independent contractors), and tax returns from the past few years. These documents establish your earning history and can demonstrate a pattern of income. If you're an hourly worker, show your typical weekly hours and rate. If you earn commissions, compile your sales records before and after the accident. For self-employed individuals, business bank statements, client invoices, and profit and loss statements become crucial. Next, you'll need medical documentation from your doctor explicitly stating the period during which you were unable to work due or were limited in your work capacity due to your injuries. This acts as the medical justification for your time off. Finally, a letter from your employer (if applicable) can be incredibly helpful, detailing your job responsibilities, your wage rate, the time you missed, and confirming that these absences were unpaid or resulted in a reduction of your normal earnings. Putting all this together forms a robust package to present to the insurance company, detailing precisely how much income you've lost.
Common Challenges in Proving Lost Wages
While seemingly straightforward, proving lost wages can sometimes feel like an uphill battle, especially if your income stream isn't a traditional, predictable salary. One major challenge arises for individuals with irregular income, such as those in sales relying heavily on commissions, or hourly workers whose schedules fluctuate wildly. It's difficult to pinpoint an exact "average" weekly income when one week you worked 20 hours and the next 60. In these cases, looking at a longer historical average – perhaps the last 6-12 months of earnings – becomes necessary to establish a credible baseline.
Self-employment introduces another layer of complexity. If you own a small business or work as a freelancer, there isn't an HR department to confirm your lost time or a clear "pay stub." Instead, you'll need to demonstrate loss of business income through client contracts that were cancelled or postponed, invoices that couldn't be sent, or a measurable decrease in your business's revenue traceable to your absence. Short-term employment or a recent job change before the accident can also be tricky. If you haven't been in your current role long enough to establish a consistent earning history, you might need to rely on offer letters, previous employment records, or even expert testimony to project your likely earnings. Insurance companies often try to minimize these figures, so having thorough documentation, regardless of your employment type, is absolutely critical.
The Long-Term Financial Impact: Lost Earning Capacity
Beyond the immediate loss of income, some car accident injuries can have a profound, lasting impact on your ability to earn money in the future. This is where the concept of lost earning capacity comes into play, and it's often a much larger and more complex component of an injury claim than simple lost wages. It addresses the "what if" – what if you could have continued your career trajectory unhindered by the accident?
Defining Lost Earning Capacity
Lost earning capacity isn't about the paychecks you've already missed; it's about the financial future that has been diminished or outright taken away because of your injuries. Imagine someone who was on track for promotions and significant career advancement, only to have a debilitating back injury from a car accident prevent them from ever performing their demanding job again. They might be able to work a less physically intensive job, but at a significantly reduced salary and with no prospect for the growth they once had. The difference between what they would have earned and what they can now earn is their lost earning capacity.
This type of damage considers the reduction in your ability to generate income over your entire remaining working life. It factors in whether your injuries are temporary or permanent, and how they impact your skills, training, education, and physical capabilities. It's about your reduced potential to perform work in the labor market generally, not just your specific job before the crash. This can include situations where you might still be working, but at a lower-paying job, or where your physical or cognitive limitations mean you can't work as many hours or take on the same responsibilities you once could. It's a forward-looking assessment, requiring expert analysis to truly understand the scope of the financial devastation.
Factors Influencing Lost Earning Capacity
Determining lost earning capacity is far more nuanced than calculating past wages. Many variables come into play, making it a highly individualized assessment. One significant factor is your age. A younger individual with a long career ahead of them might have a much higher claim for lost earning capacity than someone nearing retirement, simply because the period of potential lost earnings is longer. Your occupation and education are also critical. A specialized surgeon who suffers nerve damage in their hands will experience a far greater loss of earning capacity than someone whose job involves less specialized physical tasks, even if both sustain similar injuries.
The severity and permanence of your injury are paramount. A temporary injury that fully heals might lead to some lost wages, but likely no lost earning capacity. However, a spinal cord injury or a traumatic brain injury (TBI) can result in lifelong disabilities that fundamentally alter your ability to work. Pre-existing conditions can complicate matters, as insurance companies might argue your reduced capacity is due to an older ailment, not the accident. Finally, your past earning history, career trajectory, and any unique skills or training you possess are all evaluated to project what your earnings would have been without the accident. Understanding how car accident settlement calculations take these complex factors into account is crucial.
The Difference Between Lost Wages and Lost Earning Capacity
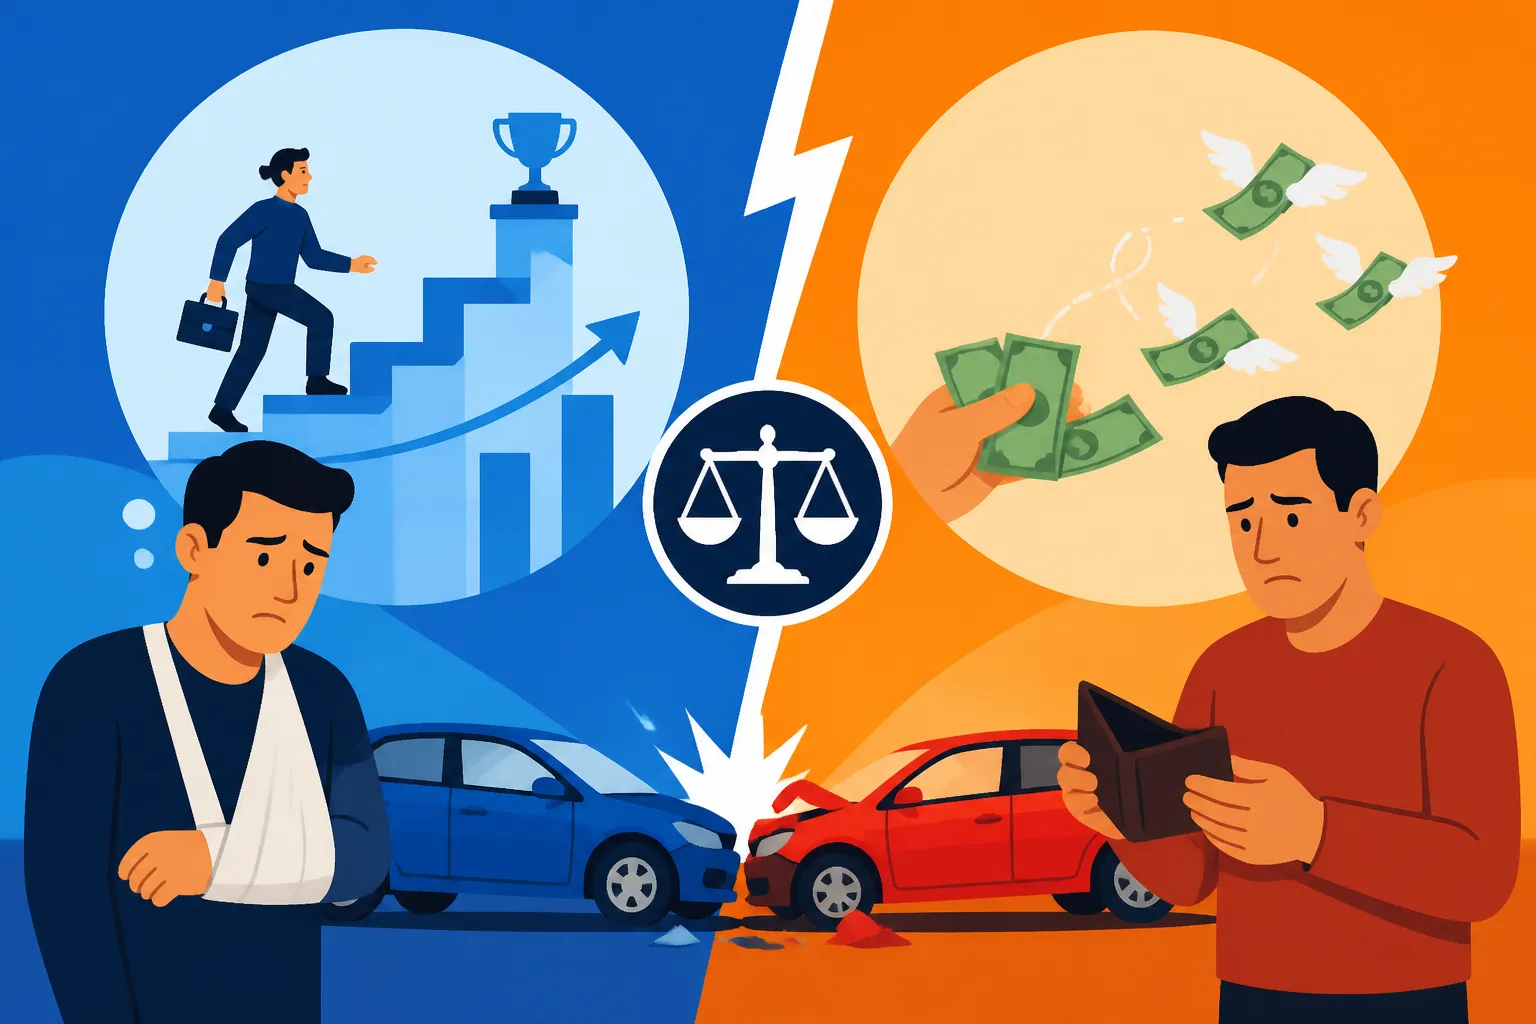
While both lost wages and lost earning capacity address financial losses due to an inability to work after a car accident, they target different timeframes and require different types of proof. Think of them as two distinct but related categories within your overall economic damages claim.
Lost wages are essentially backward-looking. They compensate you for the actual income you missed from the date of the accident up to the present day, or up to the point where your doctor says you've reached maximum medical improvement (MMI) and can return to work, even if it's in a modified capacity. It's a quantifiable loss based on past paychecks and a clear period of absence. For example, if you broke your arm in a car accident and couldn't type for six weeks, the income you missed during those six weeks would be your lost wages.
Lost earning capacity, on the other hand, is forward-looking and more speculative. It compensates you for the future potential income you will lose over the rest of your working life because your injuries have permanently or long-term diminished your ability to earn as much as you otherwise would have. This might apply if that broken arm never fully heals, leaving you with chronic pain or limited mobility that prevents you from ever going back to your high-paying typing job and instead forces you into a lower-paying role. The difference in income you'll likely experience over decades, discounted to present value, is your lost earning capacity. It's about your reduced competitive edge in the job market, not just the specific paychecks you've missed. Many Factors That Affect Your Settlement Amount will come into play when dealing with these distinct damage types.
Here's a quick table to summarize the core distinctions:
| Feature | Lost Wages | Lost Earning Capacity |
|---|---|---|
| Timeframe | Past and present (from accident to MMI) | Future (from MMI to projected retirement) |
| Focus | Actual income missed due to inability to work | Diminished ability to earn income in the future |
| Proof Required | Pay stubs, W2s, employer letters, medical notes | Expert vocational/economic reports, extensive medical records |
| Quantification | Relatively direct calculation based on history | Complex projection, discounted to present value |
| Nature of Loss | Specific, measurable income | Potential, long-term reduction in earning potential |
Proving Lost Earning Capacity: A More Complex Battle
Unlike lost wages, which often come with clear documentation, proving lost earning capacity is a significantly more intricate process. It requires forecasting future events and demonstrating how an injury will impact a person's entire career trajectory, which is inherently challenging and often hotly contested by insurance companies. This is where expert testimony becomes not just helpful, but often absolutely essential.
The Role of Medical Experts and Vocational Specialists
To successfully claim lost earning capacity, you can't just assert that your future earning potential is diminished. You need concrete, expert opinions to back up your claim. This is where medical experts and vocational specialists play pivotal roles. Your treating physicians, orthopedists, neurologists, or other specialists will provide crucial medical evidence regarding the nature and extent of your injuries. They will detail how these injuries have resulted in permanent impairments, what your physical and mental limitations are, and what activities you can no longer perform. This medical testimony forms the foundation, establishing the cause of the reduced earning capacity.
Building on this, a vocational specialist (sometimes called a vocational rehabilitation expert) steps in. This expert assesses how your medical limitations translate into real-world job market limitations. They analyze your pre-accident job, education, skills, and experience, then compare it with your post-accident physical and mental capabilities. They'll perform a detailed labor market analysis to determine what jobs you can perform now, what their typical salary ranges are, and how your earning potential has changed. They might also assess your residual transferable skills and whether retraining is feasible or necessary. This specialist essentially builds a bridge between your medical condition and the economic impact it has on your career, providing a dollar figure for your lost earning capacity. They are critical in claims involving complex injuries like a Traumatic Brain Injury TBI From a Car Accident or severe spinal injuries.
Documentation Needed for Lost Earning Capacity Claims
Because lost earning capacity is a projection into the future, the documentation required is extensive and focuses on painting a complete picture of your past potential and present limitations. It goes far beyond pay stubs. You'll need comprehensive medical records, including diagnostic tests, doctor's notes, treatment plans, and prognoses that clearly outline the permanence or long-term nature of your injuries and the resulting functional limitations. This is often where the concept of What Is Maximum Medical Improvement MMI becomes relevant, as the assessment of future capacity often occurs after you've reached this point in your recovery.
Beyond medical records, a full history of your employment is crucial. This includes past job descriptions, performance reviews, promotion records, and salary increases. Educational transcripts, certifications, and any specialized training documents demonstrate your marketable skills and potential career path. If you had specific career goals or plans that were derailed, evidence of these, such as enrollment in a higher education program or a promotion offer, can also be highly valuable. Finally, the detailed reports from both your medical experts and vocational specialists, which often incorporate economic analyses to calculate the present value of future lost income, are the cornerstones of this type of claim. Without this robust documentation, convincing an insurance company or a jury of your future losses becomes incredibly difficult.
Challenges in Quantifying Future Losses
Quantifying future losses, like lost earning capacity, is inherently challenging because it involves predicting the unpredictable. Life rarely follows a linear path, and projecting decades into the future is filled with uncertainties. One major challenge is the speculative nature of career trajectory. How can anyone definitively say what promotions you would have received, what raises you would have earned, or what advancements your industry might have seen over the next 20, 30, or 40 years? Insurance companies will often argue that your projections are overly optimistic, failing to account for normal economic downturns, job changes, or even personal choices that might have impacted your career regardless of the accident.
Another hurdle is accounting for variables like inflation, interest rates, and the discounting of future earnings to their present value. An economist usually performs these complex calculations, but even they rely on assumptions that can be challenged. Furthermore, proving that your entire future earning potential is compromised, rather than just being unable to perform your specific pre-accident job, requires showing that you are less competitive in the broader job market. This can be difficult if you have transferable skills or if your injuries allow for some form of work, even if it's not what you're used to. Insurance adjusters will often look for any reason to poke holes in these projections, which is why the meticulous work of vocational and economic experts is so vital.
Navigating the Claim Process for Wage and Earning Capacity Losses
Dealing with the aftermath of a car accident is already stressful, but trying to navigate the complex world of insurance claims, especially when significant financial losses are involved, can feel overwhelming. It's important to understand how insurance companies approach claims for lost wages and, particularly, lost earning capacity, and what steps you can take to protect your right to fair compensation.
How Insurance Companies Evaluate These Claims
Insurance companies are businesses, and their primary goal is to minimize payouts. When it comes to claims for lost wages and lost earning capacity, they will scrutinize every detail with a critical eye. For lost wages, they'll look for any inconsistencies in your employment history, question the duration of your time off, and might even try to suggest you could have returned to work sooner or in a modified capacity. They'll often challenge the legitimacy of your documentation, especially if you have an irregular income or are self-employed.
For lost earning capacity, their skepticism ramps up significantly. They will almost certainly challenge the opinions of your medical and vocational experts. They might hire their own "independent medical examination" doctors to dispute the severity or permanence of your injuries, or their own vocational experts to argue that you have more transferable skills and can earn more than your experts suggest. They'll look for any pre-existing conditions to attribute your limitations to something other than the accident. Their goal is to poke holes in the speculative nature of future loss claims, arguing that your projections are exaggerated or that your future earnings would have been lower anyway due to other factors. You need to be prepared for this aggressive stance and have robust evidence to counter it.
Strategies to Maximize Your Compensation
Maximizing your compensation for both lost wages and lost earning capacity requires proactive steps from the moment of the accident. The first and most crucial strategy is meticulous record-keeping. This means keeping every single document related to your accident, injuries, and finances. This includes medical bills, doctor's notes, prescriptions, physical therapy records, and any communication with healthcare providers. For financial documentation, retain all pay stubs, W2s, tax returns, and employer letters. If you're self-employed, keep a detailed log of missed work, cancelled projects, and reduced income.
Secondly, always prioritize prompt medical attention and follow through with all recommended treatments. Not only is this vital for your recovery, but it also creates a clear, unbroken chain of medical documentation linking your injuries to the accident and justifying your inability to work. Gaps in treatment can be used by insurance companies to suggest your injuries aren't serious or aren't accident-related. Finally, consider seeking legal representation, especially if your injuries are severe or your claim involves significant lost earning capacity. An experienced car accident attorney understands the nuances of these claims and can help you gather the necessary evidence, engage the right experts, and negotiate effectively with insurance companies to ensure you receive fair compensation. They know how to effectively counter the tactics employed by insurers, such as when they unfairly blame you, which can dramatically affect your settlement.
The Impact of Comparative Fault on Your Claim
It's a harsh reality that in many states, if you are found to be partially at fault for an accident, it can directly reduce the amount of compensation you receive, including for your lost wages and lost earning capacity. This legal principle is known as comparative negligence. While the specifics vary by state – some follow a "pure" comparative negligence rule, while others have "modified" rules like the 50% or 51% bar – the basic idea is the same: your damages are reduced by your percentage of fault. For example, in a state like California, which follows pure comparative negligence, if you're deemed 20% responsible for the crash and your total damages (including lost wages and lost earning capacity) are assessed at $100,000, your final award would be reduced by 20% to $80,000.
This means that even if you've done everything right in documenting your financial losses, an argument over fault can significantly erode your recovery. Insurance companies will often try to shift as much blame as possible onto you to reduce their payout. Understanding how What Happens If You're Partially at Fault impacts your claim is vital. It underscores the importance of gathering evidence at the scene, such as photos, witness statements, and police reports, to clearly establish the other driver's fault. If you find yourself in a situation where the other driver blames you, strong evidence and legal counsel can be essential to protect your claim.
Legal Considerations and Expert Assistance
When you're dealing with injuries and the financial fallout of a car accident, the legal landscape can feel like a maze. Understanding when to seek legal help, what a lawyer can do for you, and the critical deadlines involved can make all the difference in securing the compensation you need.
When to Seek Legal Counsel for Lost Wages and Earning Capacity
You might think that if your lost wages are straightforward, you can handle the claim on your own. However, even seemingly simple lost wage claims can become complicated, and claims involving lost earning capacity almost always benefit from legal expertise. You should definitely consider seeking legal counsel if your injuries are severe or long-lasting, especially if they prevent you from returning to your pre-accident job or significantly reduce your capacity to earn a living in the future. If you've been diagnosed with a Herniated Disc From a Car Accident or a similar serious injury, a lawyer becomes indispensable.
Another clear sign is when the insurance company denies your claim, offers a lowball settlement that doesn't adequately cover your losses, or starts to blame you for the accident. If you're facing high medical bills and can't work, the stakes are simply too high to navigate alone. Also, if your income is irregular, if you're self-employed, or if you were recently unemployed or between jobs when the accident occurred, an attorney can help you establish a credible claim for your financial losses. Essentially, if you have any doubt about receiving fair compensation for both your immediate and long-term financial impacts, it's wise to consult with an attorney.
The Role of a Car Accident Lawyer
A car accident lawyer doesn't just fill out forms; they become your advocate, protecting your rights and fighting for the compensation you deserve. When it comes to lost wages and lost earning capacity, their role is multifaceted and incredibly valuable. First, they help you gather and organize all the necessary documentation, ensuring nothing is overlooked. This includes working with your doctors to get detailed medical reports and connecting you with vocational and economic experts who can accurately assess and quantify your lost earning capacity.
They handle all communication and negotiations with the insurance companies, shielding you from their often aggressive tactics. They know how to counter low offers and provide the evidence needed to justify a higher settlement. If negotiations fail, they are prepared to take your case to court, building a strong argument to present to a judge and jury. Furthermore, a lawyer understands the intricacies of How Car Accident Settlements Are Calculated and can ensure all aspects of your damages, including pain and suffering, are properly accounted for. They can also explain how their fees work, often on a contingency basis, meaning you typically don't pay upfront. For a detailed breakdown, you might want to read more about How Much Does a Car Accident Lawyer Cost.
Understanding the Statute of Limitations
One of the most critical legal considerations in any car accident claim, especially those involving substantial financial losses like lost earning capacity, is the statute of limitations. This is a strict legal deadline that dictates how long you have from the date of the accident to file a personal injury lawsuit. If you miss this deadline, you will almost certainly lose your right to pursue compensation, regardless of the severity of your injuries or the strength of your evidence. The exact timeframe varies significantly from state to state. For instance, in California, the statute of limitations for most personal injury claims is generally two years from the date of the injury. In Texas, it's also typically two years.
It's absolutely crucial to be aware of the specific statute of limitations in your state. While many claims settle out of court, having the option to file a lawsuit keeps the pressure on the insurance company to negotiate fairly. If you wait too long, that leverage disappears. An attorney can help you understand the specific deadline for your case and ensure all necessary legal steps are taken in a timely manner. This is one of the most compelling reasons to contact a lawyer as soon as possible after an accident, even if you're not sure you'll need one. You can read more about the specific timelines in your state, for example, about the Statute of Limitations for Car Accidents in California.
Disclaimer
Please remember that this article provides general information and is not intended as legal advice. Every car accident claim is unique, and the laws governing lost wages, lost earning capacity, and other damages can vary significantly by jurisdiction. For personalized advice regarding your specific situation, it is always recommended to consult with a qualified personal injury attorney.