What Are Special Damages vs General Damages?
When you've been in a car accident, especially one that wasn't your fault, the immediate aftermath can feel like a whirlwind. Beyond the shock and the physical pain, a significant source of stress often comes from navigating the confusing world of insurance claims and compensation. Understanding what you can actually recover financially is crucial, and that's where the distinction between "special damages" and "general damages" becomes incredibly important. This guide will walk you through these two fundamental types of compensation, helping you understand what they cover, how they're calculated, and why knowing the difference can profoundly impact your car accident claim.
What Are Damages in a Car Accident Claim?
After a car accident, "damages" isn't just a fancy legal term; it's the core of how you get compensated for everything you've lost or endured because of someone else's negligence. It's the mechanism designed to put you back in the position you were in before the collision, as much as money possibly can. Too often, people think of damages only in terms of their smashed-up car, but the reality is far more expansive, covering everything from the smallest out-of-pocket expense to the deepest emotional scars.
The Goal of Compensation
Imagine a perfect world where a car accident never happened. You'd be at work, enjoying your hobbies, living your life without pain or financial strain from the crash. The goal of compensation, in the legal sense, is to achieve this state as closely as possible. It's about making you "whole" again. Of course, money can't erase a traumatic experience or fully heal a severe injury, but it can alleviate the financial burdens and provide some measure of recognition for your suffering. This includes addressing both the obvious, quantifiable losses and the more personal, subjective impacts on your life. Without a clear understanding of all the ways an accident has harmed you, it’s impossible to pursue a fair settlement. This guide delves deeper into What Are Damages in a Car Accident Claim?.
Beyond Just Car Repairs
It's natural to first worry about your vehicle after a crash. Where will you get it fixed? How much will it cost? Do you need a rental car? These are all valid concerns, and they certainly fall under the umbrella of damages. However, focusing solely on property damage is a common pitfall. The true scope of damages extends far beyond the sheet metal and paint. It encompasses your physical well-being, your mental health, your ability to work, and even your quality of life. Many people underestimate the hidden costs of an accident—the time off work for doctor's appointments, the ongoing physical therapy, the emotional toll of dealing with pain and disruption. Ignoring these broader categories of harm means leaving significant money on the table and not truly recovering everything you're entitled to.
Understanding Special Damages: The Tangible Costs
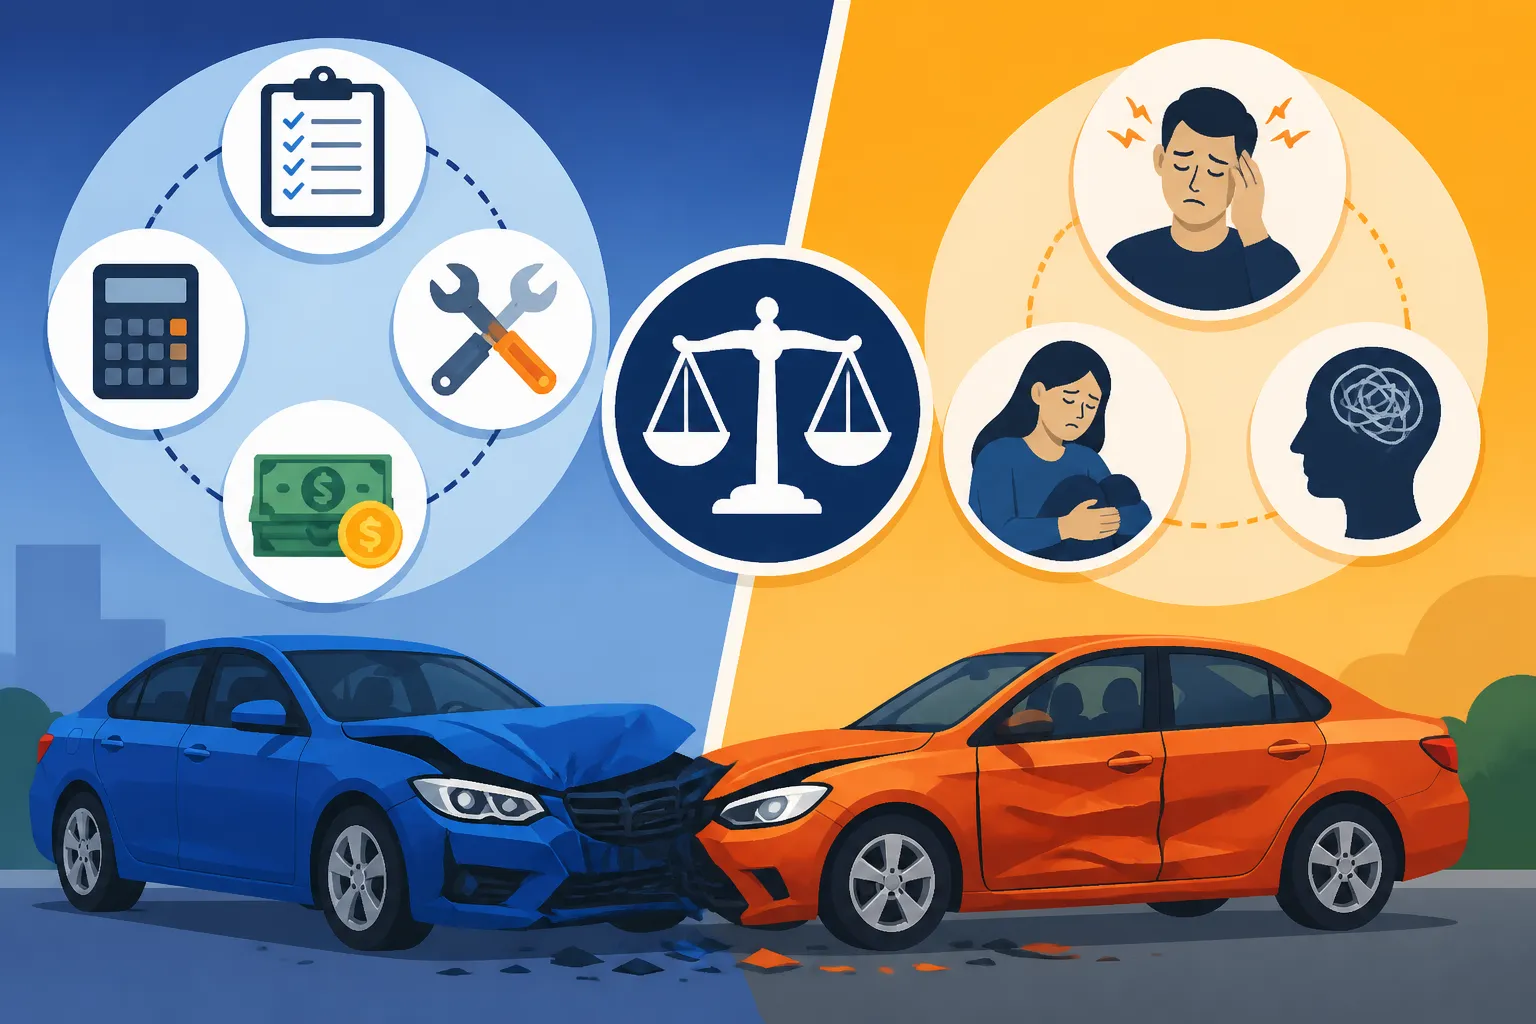
Special damages, also known as economic damages, are the most straightforward part of your car accident claim. Think of them as the concrete, quantifiable losses that come with a specific dollar amount. These are the expenses you can point to on a bill, a receipt, or a pay stub. They're objective and relatively easy to calculate, making them a crucial foundation for any personal injury claim. When an insurance adjuster looks at your claim, they'll often start by tallying these "hard numbers."
Medical Expenses: Past and Future
One of the most significant categories of special damages is medical expenses. From the moment the ambulance arrives on the scene to months or even years of rehabilitation, every single medical cost directly related to your accident falls into this category. This isn't just about the emergency room visit right after the crash. It includes:
- Ambulance rides: The initial cost of transport to the hospital.
- Emergency room bills: For initial assessment, diagnosis, and immediate treatment.
- Hospital stays: If your injuries were severe enough to require admission.
- Doctor's visits: Follow-up appointments with your primary care physician, specialists (orthopedists, neurologists, chiropractors), and therapists.
- Prescription medications: For pain management, muscle relaxers, anti-inflammatories, etc.
- Physical therapy and rehabilitation: Often a long-term process, especially for injuries like whiplash, back pain, or fractures.
- Diagnostic tests: X-rays, MRIs, CT scans, and other imaging to diagnose the extent of your injuries.
- Surgeries: If required to repair damaged bones, ligaments, or other tissues.
- Medical devices: Crutches, wheelchairs, braces, adaptive equipment.
- Future medical care: This is a big one. If your doctor determines you'll need ongoing treatment, therapy, or even future surgeries, those projected costs can be included. This is often where expert medical testimony becomes vital, as it requires a professional opinion on your long-term prognosis and care needs. Properly accounting for these future costs is complex but critical for a full recovery, as discussed in detail in guides like What Is Maximum Medical Improvement MMI?.
It's absolutely critical to keep meticulous records of all these expenses. Every bill, every co-pay receipt, every prescription—they all contribute to the total calculation of your special damages. Don't throw anything away, even if your health insurance covers part of it initially, because your claim is for the total cost incurred due to the accident. Understanding How Medical Bills Are Paid From a Settlement is also key to tracking these expenses.
Lost Wages and Earning Capacity
Another major component of special damages is the income you've lost because you couldn't work after the accident. If your injuries prevent you from performing your job duties, even temporarily, that lost income is a direct financial hit. This can include:
- Lost salary or wages: The actual income you missed out on due to time off for recovery, doctor's appointments, or inability to perform your job. This applies whether you're hourly, salaried, or self-employed.
- Lost commissions or bonuses: If your ability to earn these was directly impacted by your absence or reduced performance.
- Lost benefits: Such as contributions to your 401k, health insurance premiums, or other employer-provided perks.
- Lost vacation or sick time: If you had to use your paid time off to cover recovery instead of for leisure or other illnesses, that's a calculable loss.
But it goes beyond just the immediate past. If your injuries are so severe that they permanently affect your ability to earn at the same level you did before the accident, you might be able to claim for loss of earning capacity. This is a projection of future lost income over your working lifetime. For instance, if a construction worker sustains a debilitating back injury that prevents them from ever lifting heavy objects again, they may have to retrain for a lower-paying desk job. The difference in their earning potential over the remainder of their career would be a part of their special damages. This calculation often involves vocational experts and economists and can significantly increase the value of your claim. This complex aspect is covered more in depth in posts like How Lost Wages Are Calculated in a Settlement.
Property Damage and Related Costs
While we established that damages go beyond your car, property damage is definitely a tangible, quantifiable loss. This category covers the direct costs of repairing or replacing your vehicle, but it also includes other related expenses that stem from the damage:
- Vehicle repair costs: Estimates from body shops for fixing your car. If the car is declared a Total Loss Explained: What Happens When Your Car Is Totaled, then it's the fair market value of the vehicle before the accident.
- Rental car expenses: The cost of renting a car while yours is being repaired or while you're shopping for a replacement. Insurance companies typically have limits on these, so it's good to understand your policy.
- Towing and storage fees: The cost of getting your damaged vehicle from the accident scene to a repair shop or storage facility.
- Damage to other personal property: This could include items inside your vehicle that were damaged in the crash, such as a laptop, cell phone, child car seat, or even special equipment for hobbies or work.
- Diminished value: Even if your car is repaired, its market value might be less than it was before the accident simply because it now has an accident history. This "diminished value" can also be claimed as special damages, particularly for newer or high-value vehicles.
Again, documentation is key. Keep all repair estimates, bills, rental agreements, towing receipts, and photos of damaged personal items. These pieces of evidence make it clear to the insurance company exactly what your out-of-pocket costs have been.
Understanding General Damages: The Intangible Toll
While special damages deal with the concrete financial losses, general damages (also known as non-economic damages) address the profound, yet often invisible, ways an accident can impact your life. These are the subjective, non-monetary losses that don't come with a bill or receipt but are no less real or deserving of compensation. They represent the pain, suffering, and disruption to your quality of life caused by the accident. Because they don't have a fixed price tag, valuing general damages is often more challenging and frequently becomes a point of contention with insurance companies. This distinction is a key part of understanding Economic vs Non-Economic Damages in Injury Claims.
Pain and Suffering: Physical and Emotional
This is perhaps the most widely recognized category of general damages. "Pain and suffering" encompasses a broad spectrum of physical and emotional distress you endure due to your injuries. It's not just about the moment of impact or the immediate recovery; it's about the ongoing discomfort, agony, and mental anguish that can linger for weeks, months, or even years.
- Physical Pain: This includes the acute pain of the injury itself, chronic pain that develops over time, and the discomfort associated with medical procedures, surgeries, and physical therapy. For instance, the persistent throbbing from a herniated disc, the stiffness of whiplash, or the burning sensation of nerve damage are all forms of physical pain. Even something like a broken arm, while it eventually heals, involves weeks of severe pain, discomfort from casts or surgeries, and limitations on daily activities.
- Emotional Suffering: This component is just as vital. Accidents are traumatic, and the emotional fallout can be significant. This might manifest as:
- Anxiety and Fear: Fear of driving again, anxiety about future medical procedures, or worry about financial stability.
- Depression: A common reaction to chronic pain, loss of independence, or inability to enjoy life.
- Grief: In cases of severe injury, grieving the loss of physical abilities, hobbies, or a previous lifestyle.
- Shock and Trauma: The initial emotional impact of the crash, which can lead to nightmares, flashbacks, or symptoms akin to PTSD.
- Frustration and Anger: Dealing with the disruption to your life, the pain, and the slow recovery process.
Proving pain and suffering often relies on detailed medical records, consistent doctor visits, therapist notes, and your own personal testimony, often recorded in a pain journal. The more thoroughly you document your pain, both physically and emotionally, the stronger your case will be for these damages. More on this can be found in Pain and Suffering Damages: What They Cover.
Loss of Enjoyment of Life
Imagine your life before the accident. What did you love to do? Perhaps you were an avid hiker, enjoyed playing with your kids, gardened every weekend, or played in a local sports league. Now, because of your injuries, you can't do those things, or at least not in the same way. This is what "loss of enjoyment of life" addresses. It's the compensation for the diminished quality of your daily existence and your inability to participate in activities that once brought you joy and fulfillment.
This can cover:
- Hobbies and recreational activities: If a shoulder injury prevents you from playing golf, or a knee injury stops you from running.
- Social activities: If chronic pain or immobility keeps you from attending social gatherings or traveling.
- Household chores and duties: Inability to perform tasks like cooking, cleaning, or yard work that you once did easily.
- Intimacy and personal relationships: The impact of physical pain or emotional distress on your relationship with your spouse or partner.
- Parental activities: Inability to lift your child, play with them actively, or participate in their school events.
This damage is about acknowledging that life isn't just about avoiding pain; it's about experiencing joy and participating fully. When an accident robs you of these capacities, it's a profound loss that deserves compensation. Documenting this involves keeping a journal of activities you miss or find difficult, and sometimes even getting testimony from family and friends about the changes they've observed in your lifestyle and mood.
Emotional Distress and Mental Anguish
While related to pain and suffering, emotional distress and mental anguish specifically focus on the psychological and psychiatric impact of the accident. This can be a particularly debilitating aspect of a car crash, often lingering long after physical wounds have healed. It goes beyond simple sadness or frustration and delves into more severe psychological conditions that may require professional intervention.
This category includes:
- Post-Traumatic Stress Disorder (PTSD): Flashbacks, nightmares, severe anxiety, avoidance of driving, hypervigilance, and other debilitating symptoms triggered by the accident. This is a recognized medical condition that significantly impacts daily life.
- Severe Anxiety and Panic Attacks: Developing a constant state of nervousness, panic attacks when driving or thinking about the accident, or generalized anxiety disorder.
- Clinical Depression: A diagnosable condition characterized by persistent sadness, loss of interest in activities, changes in sleep or appetite, and feelings of worthlessness.
- Sleep Disturbances: Insomnia, nightmares, or other difficulties sleeping due to pain, anxiety, or trauma.
- Development of Phobias: Such as vehophobia (fear of driving or riding in a car).
To support a claim for emotional distress, it's crucial to seek professional help. Seeing a psychologist, psychiatrist, or licensed therapist not only provides you with necessary treatment but also generates medical records that document your condition, diagnosis, treatment plan, and prognosis. These records are invaluable in demonstrating the severity and impact of your mental anguish on your life. Without professional diagnosis and treatment, it's incredibly difficult to claim significant compensation for these intangible harms, as insurers will often dispute their severity or connection to the accident. Many people suffer from PTSD and Emotional Distress After a Car Accident, and this is a legitimate area for damages.
The Big Difference: Proving Each Type of Damage
While both special and general damages aim to compensate you for losses suffered in a car accident, the way you prove them in a claim is fundamentally different. One relies on cold, hard numbers, while the other requires a more narrative, evidence-based approach to demonstrate impact. Understanding these distinct methods of proof is vital for building a strong case.
Documenting Economic Losses
Proving special damages is all about the paperwork. These are typically straightforward because they come with a paper trail. The key is thoroughness and organization. Every single bill, receipt, invoice, and statement related to your accident needs to be collected and meticulously maintained.
For medical expenses, this means:
- Collecting all hospital bills, doctor's invoices, physical therapy statements, and pharmacy receipts.
- Obtaining copies of your medical records that detail your injuries, diagnoses, treatments, and prognosis. These records directly link your expenses to the accident and demonstrate the necessity of the care.
- If future medical care is anticipated, you'll need a medical expert (your treating physician or an independent medical examiner) to provide a report outlining the expected duration and cost of that care.
For lost wages, you'll need:
- Pay stubs or income statements from before and after the accident to show your regular earnings.
- A letter from your employer confirming your missed workdays and salary or wage information.
- For self-employed individuals, tax returns, invoices, and business records can establish income loss.
- If claiming lost earning capacity, an economic expert might be required to project future income losses, taking into account factors like your age, profession, and career trajectory.
For property damage and other expenses, gather:
- Repair estimates from qualified mechanics or body shops.
- Receipts for towing, storage, and rental car costs.
- Documentation (receipts, photos, sworn statements) for any other personal property damaged in the crash.
The more complete and organized your documentation for special damages, the less room an insurance company has to dispute the actual monetary value of these losses. They are often seen as objective facts. This diligent collection of evidence is critical for demonstrating How to Prove Injuries in a Car Accident Claim.
Establishing Non-Economic Harm
Proving general damages is often where the real challenge lies, because there isn't a simple invoice for "pain" or a bill for "loss of enjoyment." Instead, you need to paint a comprehensive picture of how the accident has negatively impacted your life. This involves a combination of medical evidence, personal testimony, and sometimes expert opinions.
Here’s how you establish non-economic harm:
- Medical Records and Expert Testimony: Your medical records are paramount. They don't just show your physical injuries; they document the pain you reported to doctors, the limitations you experienced, and any diagnoses of psychological conditions like PTSD or depression. A doctor's testimony about the severity of your pain, the duration of your recovery, or the prognosis for chronic conditions is incredibly powerful. Mental health professionals' notes and diagnoses are crucial for emotional distress claims.
- Personal Journals and Diaries: Keeping a daily journal where you record your pain levels, emotional state, difficulties with daily tasks, missed activities, and overall struggles can be a powerful tool. It provides a real-time, personal account of your suffering and helps create a narrative that resonates.
- Witness Testimony: Friends, family members, and co-workers can attest to the changes they've observed in your personality, activities, and overall quality of life since the accident. Their unbiased observations can corroborate your claims of pain, suffering, and loss of enjoyment.
- Photographs and Videos: Visual evidence, such as photos of severe injuries, scars, or even videos showing your struggles with simple tasks (if appropriate and respectful of your privacy), can powerfully illustrate the impact of the accident.
- Expert Witnesses: In complex cases, a pain management specialist, psychologist, or vocational expert might provide testimony on the extent of your suffering, its impact on your life, and any long-term psychological effects.
The key to establishing general damages is consistency and credibility. The more consistently your suffering is documented across different sources—medical records, your own words, and observations from others—the stronger your argument becomes. This comprehensive approach helps in demonstrating How to Document Pain and Suffering.
How Insurance Companies Approach Special vs. General Damages
Dealing with insurance companies after an accident can be incredibly frustrating. They're in the business of minimizing payouts, and their approach to special versus general damages often highlights this objective. They treat these two categories very differently, and understanding their perspective can help you prepare for negotiations.
The Insurer's Perspective on Special Damages
For insurance companies, special damages are generally easier to handle, at least in theory. Because these damages are quantifiable and backed by bills and receipts, there's less room for subjective interpretation. An adjuster can look at a medical bill for $5,000, a car repair estimate for $3,000, and lost wage statements for $2,000, and easily calculate a total of $10,000 in special damages.
However, "easier to handle" doesn't always mean "easier to get paid." Insurers will still scrutinize these costs to ensure they are:
- Reasonable and Necessary: They might argue that certain medical treatments were excessive, unrelated to the accident, or that you prolonged your recovery. They may question the necessity of certain diagnostic tests or the duration of physical therapy.
- Directly Caused by the Accident: They'll look for any pre-existing conditions and try to attribute your medical expenses to those, rather than the collision. This is why thorough medical documentation linking your current injuries specifically to the accident is so important.
- Documented Properly: If you have missing receipts or incomplete records, they'll use that as a reason to reduce or deny those specific claims.
Essentially, while the nature of special damages is clear, the amount they're willing to pay for them can still be heavily negotiated. They want proof for every dollar. Being prepared with detailed records can significantly streamline this process and prevent them from unduly reducing your claim. This is particularly relevant when considering How Insurance Companies Determine Who Is at Fault.
The Challenge of Valuing General Damages
This is where things get tricky, and where insurance companies often push back the hardest. Since general damages are subjective and don't come with a fixed price tag, insurance adjusters have a lot more leeway to devalue them. There's no standardized "pain-o-meter" or "suffering calculator."
Insurance companies typically use a few common methods or tactics to value (and often devalue) general damages:
- The Multiplier Method: A common (though often unstated) internal method is to take the total amount of special damages and multiply it by a certain number (often between 1.5 and 5, depending on the severity of injuries). For example, if your special damages are $10,000 and the adjuster decides on a 2x multiplier, your general damages would be valued at $20,000. The challenge for you is that the multiplier they choose will always be on the lower end unless you can strongly justify a higher one. Factors like objective evidence of injury, length of recovery, impact on daily life, and clear emotional distress can influence this multiplier.
- Per Diem Method: Less common, but sometimes used for short-term pain, this assigns a daily value to your pain and suffering from the date of injury until maximum medical improvement.
- Downplaying Severity: Adjusters will frequently try to minimize the extent of your pain and suffering. They might argue that your injuries were minor, that your emotional distress is exaggerated, or that your loss of enjoyment of life isn't as significant as you claim. They may point to gaps in your medical treatment or delays in seeking care as reasons to doubt the severity of your general damages.
- Focusing on Medical Bills Only: They might try to link general damages solely to the dollar amount of your medical bills, ignoring the deeper impact on your life. This is why it's so important to have strong evidence for all aspects of your general damages, not just what's in your doctor's notes.
- Claiming Pre-existing Conditions: As with special damages, they will try to attribute any pain or emotional distress to prior conditions, even if the accident exacerbated them.
Because valuing general damages is so subjective, this is often the area where an experienced personal injury attorney can make the most significant difference. They understand how to present compelling evidence and negotiate effectively to ensure your pain and suffering are adequately recognized. When dealing with a lowball offer, knowing How to Counter a Low Settlement Offer is essential.
Maximizing Your Claim: Documenting Both Types of Damages
Navigating a car accident claim is rarely straightforward, and the key to securing fair compensation lies in meticulous documentation for both special and general damages. Without robust evidence, even the most legitimate claims can be undervalued or denied. Think of yourself as building a comprehensive story, one backed by facts, figures, and personal experience, illustrating every way the accident has impacted your life.
Detailed Record Keeping for Special Damages
For special damages, the mantra is "if it's not documented, it didn't happen." Every single expense, no matter how small it seems, contributes to the overall picture of your financial loss.
Here's how to ensure you're keeping detailed records:
- Create a Dedicated Folder or Digital File: As soon as the accident happens, start a physical folder or a cloud-based folder on your computer (Google Drive, Dropbox, etc.) specifically for your accident documents. This keeps everything in one place and prevents important papers from getting lost.
- Keep Original Receipts and Bills: For every medical appointment, prescription, co-pay, therapy session, mileage to appointments, car repair, rental car, or damaged personal item, get and keep the original receipt or an official bill. Make copies if you need to submit them elsewhere, but always keep your originals.
- Maintain a Mileage Log: If you're driving to doctor's appointments, therapy, or the pharmacy, keep a log of the dates, destinations, and mileage. This travel time and cost can be reimbursed as special damages.
- Track Lost Wages Accurately: Get a letter from your employer confirming missed workdays and salary. Keep copies of your pay stubs from before and after the accident. If you're self-employed, compile invoices, bank statements, and tax returns to prove income loss.
- Document Property Damage Fully: Get multiple repair estimates for your vehicle. Take clear photos of the damage from various angles, both at the scene of the accident and before/during repairs. If your car is totaled, have all relevant paperwork showing its pre-accident value.
- Organize and Categorize: Within your folder, categorize documents by type (medical bills, lost wages, property damage, etc.) and date. This makes it easy to retrieve specific information when needed and present a clear, organized picture to the insurance company or your attorney.
Consistent and comprehensive record-keeping significantly reduces the chances of an insurance adjuster disputing your out-of-pocket costs. It provides irrefutable proof of your financial losses. This also aligns with the advice on What to Do After a Car Accident: Step-by-Step.
Building a Narrative for General Damages
Since general damages are subjective, you need to build a compelling narrative that vividly portrays your pain, suffering, and the impact on your life. This isn't just about listing symptoms; it's about showing how those symptoms have changed who you are and what you can do.
Key elements for building this narrative include:
- Medical Treatment Consistency: The most powerful evidence for general damages comes from consistent medical treatment. Regularly attending doctor's appointments, physical therapy sessions, and mental health counseling not only aids your recovery but also creates a continuous record of your pain, limitations, and emotional struggles. Gaps in treatment can be used by insurers to argue your injuries weren't that severe or that your pain subsided. Seeking treatment for Delayed Injury Symptoms After a Car Accident is also vital for your claim.
- Pain and Symptom Journal: This is invaluable. Keep a daily or weekly journal detailing:
- Pain Levels: Use a 1-10 scale.
- Nature of Pain: Is it throbbing, sharp, dull, burning?
- Impact on Daily Activities: What specific tasks can you no longer do, or find difficult? (e.g., "Couldn't lift my child today," "Had to skip my pottery class," "Couldn't sleep due to back pain").
- Emotional State: Document feelings of frustration, sadness, anxiety, fear, or depression.
- Medication Effectiveness: How well are your pain medications working?
- Therapy Progress: Note any improvements or setbacks in physical or mental therapy.
- Witness Statements: Ask family, friends, or co-workers to provide written statements or be prepared to testify about how your injuries have changed your life. They can describe your previous activities, your current limitations, your mood changes, and how the accident has affected your relationships.
- Photographs and Videos: If appropriate, photos of your visible injuries (bruises, cuts, scars, casts) over time can demonstrate the physical reality of your suffering. Videos showing you struggling with once-simple tasks can be very impactful.
- Expert Opinions: In serious cases, getting a medical expert (like a pain management specialist or a neurologist) to testify about the chronic nature of your pain or a psychologist to discuss your PTSD can significantly strengthen your claim for general damages.
- Social Media Review (Caution!): Be mindful of what you post on social media. Insurance companies often look for inconsistencies. If you claim a severe back injury but post photos of yourself hiking, it can severely undermine your claim. Assume everything you post could be seen by the insurance company.
Building a compelling narrative for general damages requires persistence and honesty. The more clearly you can articulate and demonstrate how the accident has impacted every facet of your life, the stronger your position will be for a fair settlement that reflects the true, comprehensive costs of your injuries. You might even consider if you Do You Need a Lawyer for a Car Accident? to help manage this complex process.
Here's a table to summarize the key differences:
| Feature | Special Damages (Economic) | General Damages (Non-Economic) |
|---|---|---|
| Nature | Tangible, quantifiable, direct financial losses | Intangible, subjective, non-monetary losses |
| Examples | Medical bills, lost wages, property damage, rental car costs | Pain & suffering, emotional distress, loss of enjoyment of life, disfigurement |
| Proof Required | Receipts, bills, pay stubs, invoices, medical records | Medical records, personal testimony, witness statements, psychological evaluations, pain journals |
| Calculation | Sum of actual costs | Often estimated using multipliers of special damages or per diem methods, highly subjective |
| Ease of Proof | Relatively straightforward, relies on documentation | More challenging, relies on consistency and credibility of narrative |
| Negotiation with Insurers | Scrutinized for necessity and causation; less room for dispute on value if well-documented | Highly contentious; frequently minimized due to subjective nature; more room for negotiation |
Disclaimer
Please remember that this article provides general information and guidance regarding car accident claims and damages. It is not intended as legal advice. Every car accident case is unique, and the specific laws and regulations regarding damages can vary significantly by state. For personalized advice on your specific situation, it is always recommended to consult with a qualified personal injury attorney.