What Happens After You File a Car Accident Claim?
The moments after a car accident are often a blur of confusion, anxiety, and a touch of panic. You’ve exchanged information, maybe even spoken to the police, and now you’re left with the daunting task of figuring out how to get your life, and your vehicle, back on track. Filing that initial car accident claim feels like a huge step, and it is! But it’s also just the beginning of what can often feel like a complicated and drawn-out process. This guide is here to pull back the curtain and walk you through exactly what happens after you’ve officially filed your car accident claim, so you know what to expect every step of the way.
The Immediate Aftermath of Filing Your Claim
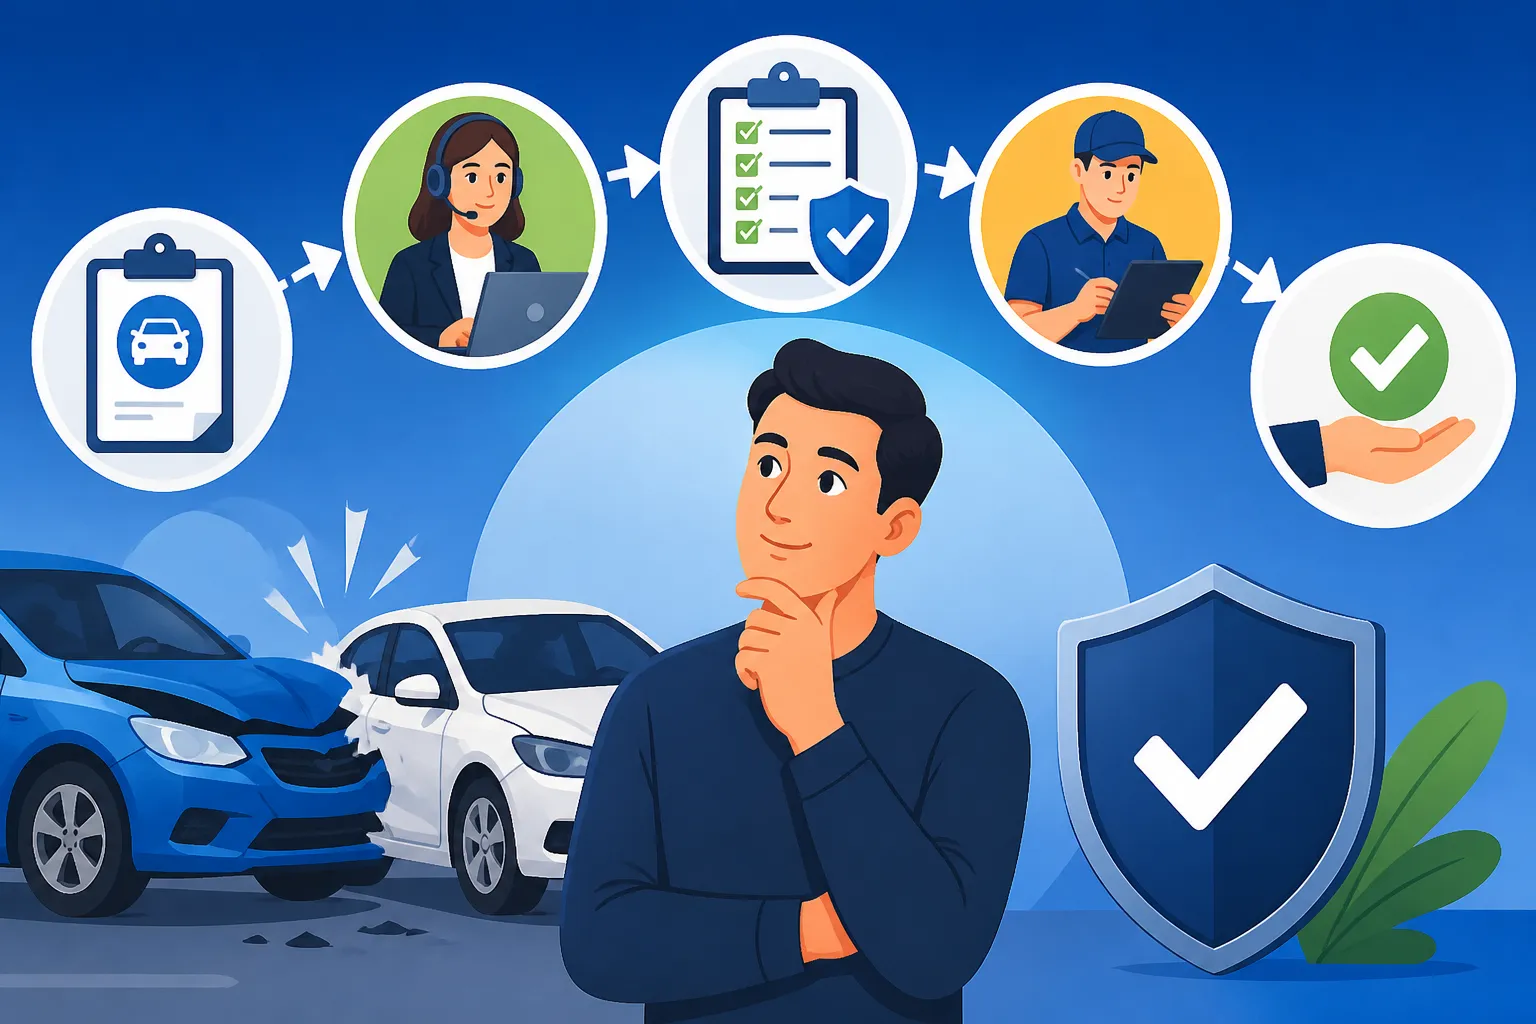
Once you've taken that first nerve-wracking step of reporting your accident to your insurance company or the other driver's insurer, a specific chain of events is set into motion. It’s natural to feel a bit adrift during this period, wondering if your claim is just sitting in a digital pile somewhere. Rest assured, things are moving, even if you don't hear back instantly. The immediate aftermath involves your insurance company acknowledging your claim and starting their preliminary internal processes.
Confirmation and Initial Contact
After you’ve submitted your claim, either online, over the phone, or through an app, the first thing you should receive is confirmation. This usually comes in the form of a claim number, which is crucial. Think of this number as the unique identifier for your entire accident saga – you’ll need it for every communication, every follow-up, and every conversation about your case. Without it, you’re just another voice on the phone.
Shortly after receiving your claim number, you can expect to hear from an insurance adjuster. This isn't just a friendly check-in; this person will be your primary point of contact and the individual responsible for managing your claim from start to finish. They'll introduce themselves, verify the details you've already provided, and explain what their next steps will be. This initial conversation is often where they start gathering more in-depth information about the accident itself, your injuries, and the damage to your vehicle. It’s important to be clear and factual, but remember, you don’t have to offer up more information than necessary, especially if you’re still feeling shaken or unsure about details.
What Your Insurance Company Does First
If you filed a claim with your own insurance company, they’ll typically swing into action to address your immediate needs, particularly if you have collision coverage for your vehicle or personal injury protection (PIP) for medical expenses. Their initial focus will often be on getting your vehicle inspected for damage. They might direct you to an approved body shop or send out an appraiser to assess the repair costs. This is often the quickest part of the process, as getting your car back on the road (or declaring it a total loss) is usually a priority.
Beyond vehicle damage, your insurer will also open a file for any bodily injury claims if you were hurt. They might advise you to seek medical attention if you haven't already, emphasizing the importance of documenting your injuries. This stage also often involves internal reviews to determine your policy’s coverage limits and benefits, ensuring they have a clear picture of what they’re financially responsible for. They'll also typically attempt to contact the other driver and their insurance company if the other party was at fault, initiating the communication that could lead to a third-party claim.
The Other Driver's Insurance: What to Expect
When you're dealing with the at-fault driver's insurance company – which is a "third-party claim" – the experience can feel a bit different, and sometimes more adversarial. Their primary goal is to protect their client (the at-fault driver) and their own bottom line. So, while they will acknowledge your claim, their initial contact might involve a bit more probing questions, perhaps even subtly trying to get you to admit some degree of fault. It's really common to feel like you're being interrogated during these calls, so stay vigilant and don’t volunteer information.
They will also typically want to inspect your vehicle and review your medical records if you’re claiming injuries. It’s crucial to understand that you are under no obligation to provide a recorded statement to the other driver's insurance company without consulting with an attorney. For more on this, check out our guide on what to do when dealing with insurance adjusters after a car accident. They're often trying to gather information that could potentially be used against you later to reduce the value of your claim. This stage sets the tone for future negotiations, so clear, concise, and carefully considered communication is key.
The Deep Dive: Investigation and Evidence Gathering
Once the initial paperwork is filed and contacts are made, the insurance companies really dig in. This is the investigation phase, where they gather all the pieces of the puzzle to understand what happened, who was responsible, and what the financial fallout looks like. It’s a critical period where the strength of your claim is built or undermined, depending on the evidence collected.
Assessing Vehicle Damage and Repairs
One of the most immediate and tangible aspects of a car accident claim is the damage to your vehicle. After you file, whether it's with your own insurer or the other party's, an adjuster or appraiser will need to assess the damage. This could involve you taking your car to a preferred body shop for an estimate, or an adjuster might come directly to your home or work to inspect the vehicle. They're looking for every dent, scrape, and structural issue related to the accident.
The appraisal process determines whether your vehicle is repairable or if it's considered a total loss. If it's repairable, they'll authorize the repairs based on the estimates, and you can get your car fixed. If it's totaled, meaning the cost of repairs exceeds a certain percentage of its actual cash value (ACV), then they'll offer you a settlement for the vehicle's value. This can be a contentious point, especially if you disagree with their valuation. Our article on How Insurance Companies Calculate Total Loss (ACV) might shed some light on this often frustrating process.
Medical Treatment and Documentation
If you suffered injuries in the accident, documenting your medical treatment is paramount. The insurance company won’t just take your word for it that you’re in pain or that you need extensive therapy. From the moment of impact, every doctor’s visit, every diagnostic test, every prescription, and every therapy session creates a paper trail that corroborates your injuries and their severity. It’s not enough to simply feel pain; you need medical professionals to diagnose and treat it.
Insurance adjusters will want to review all your medical records related to the accident. They’re looking for causation – direct links between the accident and your injuries – and they’ll also scrutinize the necessity and duration of your treatment. Maintaining consistent communication with your doctors, following their treatment plans diligently, and attending all appointments are crucial steps. Missing appointments or gaps in treatment can raise red flags for adjusters, making it seem like your injuries aren't as severe as you claim.
Gathering Key Evidence and Statements
Beyond vehicle damage and medical records, the investigation delves into the circumstances of the accident itself. This means collecting all available evidence to establish fault. This could include the police report, which can be a vital document in determining who is at fault in a car accident. If there were any witnesses, their statements will be sought. Photographs and videos taken at the scene, dashcam footage, and even surveillance camera footage from nearby businesses can be incredibly valuable.
Insurance companies will also review your driving record and the other driver’s record. They might even try to obtain a recorded statement from you, as mentioned earlier. It’s during this phase that they build their case for or against paying your claim, and for how much. They’ll look for consistency in your statements and compare them against the physical evidence. For a deeper understanding of how these different pieces of evidence fit together, our guide on how fault is determined in a car accident provides more context. This thorough evidence gathering is why it's so important to be meticulous in documenting everything from the moment the accident occurs.
The Negotiation Rollercoaster: Dealing with Adjusters
After the initial investigations are complete, the real back-and-forth often begins. This is where you’ll primarily be interacting with insurance adjusters, and it can feel like a high-stakes game of poker. Their job is to settle claims for the least amount possible, and your job is to secure fair compensation for your damages. This difference in objectives often leads to a period of negotiation.
Understanding the Role of the Adjuster
The insurance adjuster is the gatekeeper to your compensation. They are the person who evaluates your claim, determines its worth based on the evidence, and ultimately authorizes payments. It's crucial to remember that despite their sometimes friendly demeanor, they work for the insurance company, not for you. Their loyalty lies with their employer and its financial interests. They’ll analyze everything: police reports, witness statements, repair estimates, and particularly, your medical records.
Adjusters are trained to spot inconsistencies, pre-existing conditions that might be unrelated to the accident, and any gaps in your treatment that could diminish the perceived severity of your injuries. They might also inquire about your activities, social media, and employment status. Their goal is to build a case that supports a lower settlement offer. Knowing this upfront helps you approach conversations with caution and clarity, understanding that every interaction is part of their evaluation process.
Receiving and Evaluating the Initial Offer
Eventually, after reviewing all the evidence, the adjuster will present an initial settlement offer. For many people, this first offer can feel shockingly low – almost insulting, especially when you consider your medical bills, lost wages, and the pain and suffering you’ve endured. This is a common tactic, and it’s rarely the final offer. They start low to see if you’re desperate or uninformed enough to accept it quickly.
When you receive an offer, don't rush into accepting or rejecting it. Take your time to review every component. Does it cover your medical expenses, both current and future? Does it account for your lost income? What about non-economic damages like pain and suffering? You need to carefully consider all these elements. If you’re unsure how much your car accident settlement is worth, it can be really difficult to assess if an offer is fair. It's helpful to have a clear understanding of all your damages – both economic (like medical bills and lost wages) and non-economic (like pain and suffering) – before you even get to this stage.
Strategies for Counter-Negotiating
If, like most people, you find the initial offer unacceptable, the ball is back in your court to counter-negotiate. This is where having strong documentation and a clear understanding of your damages really pays off. Your counter-offer should be well-reasoned and backed by evidence. Don’t just name a higher number; explain why that number is justified. Provide specific details about ongoing medical treatment, lost earning capacity, property damage, and the impact the accident has had on your daily life.
You might need to provide additional medical bills, therapist notes, or even a letter from your employer detailing lost wages. It’s also crucial to highlight any future medical costs or pain you anticipate. Sometimes, it helps to write a formal demand letter outlining all your damages and the compensation you seek. This demonstrates you’re serious and have done your homework. Remember, patience is key here. Negotiations can involve several rounds of offers and counter-offers, so be prepared for some back-and-forth. Our guide on how to negotiate a car accident settlement offers more practical tips for this challenging phase.
Navigating Potential Hurdles and Delays
The journey through a car accident claim isn't always smooth sailing. There can be unexpected bumps, detours, and frustrating delays that test your patience and add to your stress. Understanding these potential hurdles can help you prepare and react more effectively when they arise.
Dealing with Disputes Over Fault
One of the most significant sticking points in any car accident claim is often the determination of fault. While a police report might offer an initial assessment, insurance companies can and do dispute it. If the other driver denies responsibility, or if their insurance company tries to assign you partial blame, the entire process can grind to a halt. This is particularly relevant in states that follow comparative negligence laws, where your ability to recover damages can be reduced by your percentage of fault.
For example, in California, a pure comparative negligence state, if you're found 20% at fault, your settlement will be reduced by 20%. This can feel incredibly unfair, especially if you believe the accident was entirely the other driver's fault. You might find yourself needing to gather additional evidence, such as accident reconstruction reports or expert witness testimony, to clearly demonstrate the other driver's negligence. This is a common reason why claims become protracted, as each side tries to strengthen their position on who is at fault in a T-bone accident or any other type of collision.
When Your Claim Takes Too Long
It's not uncommon for car accident claims to take weeks, months, or even over a year to resolve, especially if injuries are involved. While some delays are inherent to the process – like waiting for medical treatment to conclude or for an adjuster to complete their investigation – sometimes claims simply drag on. This can be incredibly frustrating when you have mounting medical bills, no vehicle, and potentially lost wages.
Several factors can contribute to delays: complex injuries requiring extensive treatment, disputes over liability, difficulty getting information from the other party or their insurer, or simply a high caseload for the adjuster handling your claim. If you find your claim is taking too long, it's essential to follow up regularly with your adjuster, keeping detailed records of every conversation. Documenting these interactions, including dates, times, and what was discussed, creates a paper trail that can be vital if you need to escalate your concerns. Our post on What to Do If Your Claim Is Taking Too Long dives deeper into actionable steps you can take.
What Happens If Your Claim Is Denied
Receiving a letter stating your claim has been denied can feel like a punch to the gut. It’s disheartening, frustrating, and often leaves you wondering what to do next. Insurance companies can deny claims for various reasons: asserting you were at fault, disputing the extent or causation of your injuries, claiming a lapse in coverage, or even alleging fraud.
However, a denial is not necessarily the end of the road. You usually have the right to appeal the decision. This often involves submitting new or additional evidence, clarifying misunderstandings, or providing a detailed letter refuting the reasons for denial. For instance, if they deny your injury claim saying it's a pre-existing condition, you might provide medical records showing the condition was exacerbated or re-aggravated by the accident, rather than being the sole cause. If you're facing a denied claim, our guide on What to Do If an Insurance Company Denies Your Claim can help you understand your options and next steps for appealing the decision.
Reaching a Resolution: Settlement or Legal Action
After all the investigations, negotiations, and potential hurdles, the ultimate goal is to reach a resolution. For the vast majority of car accident claims, this means a settlement. However, in some cases, when a fair agreement can't be reached, legal action becomes the necessary path.
Understanding the Settlement Process
A settlement is a formal agreement between you (the claimant) and the insurance company to resolve the claim outside of court. In exchange for an agreed-upon sum of money, you release the at-fault party and their insurer from any further liability related to the accident. This means you cannot pursue additional compensation for those specific damages in the future. Once you accept an offer, you’ll typically sign a release form, and then the insurance company will issue a payment.
The timeline for receiving your payment after a settlement can vary. It's usually within a few weeks, but complex cases or those involving structured settlements (payments made over time) might take longer. It's crucial to ensure all lienholders, such as medical providers or health insurance companies, are accounted for in the settlement distribution, to avoid unexpected bills down the line. Understanding how car accident settlements are calculated, including things like pain and suffering, is key to knowing if you're getting a fair shake.
When a Lawsuit Becomes Necessary
While most claims are settled without going to court, there are instances where a lawsuit becomes the only viable option. This usually happens when negotiations completely break down, and the insurance company is unwilling to offer a fair settlement that adequately covers your damages. This might be due to a significant dispute over fault, the severity of your injuries, or simply the insurer’s reluctance to pay out a large sum.
If a lawsuit is filed, it transitions your claim from an administrative insurance process into a legal one. This involves filing a complaint with the court, discovery (where both sides exchange information and evidence), depositions, and potentially mediation. A lawsuit doesn't automatically mean a trial, though. Many cases settle during the litigation process, sometimes even on the courthouse steps. However, preparing for trial is a serious undertaking that requires significant time, resources, and legal expertise. For a more detailed look into this, consider reading our post on How a Car Accident Lawsuit Works (If You Don't Settle).
Getting Your Payout and Closing the Claim
Once a settlement is reached, or a judgment is awarded after a trial, the final step is receiving your compensation. If you had an attorney, the settlement check will typically be sent to their office. They will then disburse the funds, first paying off any outstanding legal fees, case expenses, and medical liens (money owed to healthcare providers who treated you for the accident). The remaining balance, your net recovery, will then be paid to you.
It's a moment of relief for many, finally having the financial means to cover their expenses and move forward. However, it’s important to remember that once the check is cashed and the release forms are signed, your claim is officially closed. This means careful consideration throughout the entire process is vital, especially when deciding whether to accept a settlement offer. Ensure you've accounted for all current and future damages before you sign on the dotted line.
Disclaimer
Please remember that this article provides general information and is not a substitute for professional legal advice. Car accident claims are complex and highly dependent on the specific facts of your case and the laws of your state. Always consult with a qualified attorney or insurance professional for advice tailored to your situation.