How to File a Car Accident Claim in Georgia
Getting into a car accident can be a truly disorienting and stressful experience, leaving you shaken, injured, and often unsure of what to do next. Beyond the immediate chaos and potential pain, the thought of dealing with insurance companies, understanding complex legal terms, and navigating the claims process in Georgia can feel overwhelming. This guide is designed to cut through that confusion, offering clear, empathetic steps on exactly how to file a car accident claim in Georgia, ensuring you protect your rights and pursue the compensation you deserve.
Immediate Steps After a Car Accident in Georgia
When a car accident happens, your world can feel like it's been turned upside down in an instant. The moments right after a collision are critical, not just for your immediate safety and well-being, but also for laying the groundwork for any future car accident claim in Georgia. Taking the right steps from the get-go can make a huge difference in the outcome.
Prioritizing Safety and Seeking Medical Attention
First and foremost, your health and safety are paramount. Even if you feel fine in the immediate aftermath, adrenaline can mask pain and serious injuries.
If your vehicle is operable and it's safe to do so, move it to the side of the road or a nearby safe location to prevent further accidents. If not, activate your hazard lights and stay in your vehicle with your seatbelt fastened, if possible, until help arrives. This simple act of moving out of harm's way can prevent a secondary collision, which unfortunately happens more often than you might think on busy Georgia roadways like I-75 or GA-400. Once you're in a safer spot, or if you can't move, check yourself and any passengers for injuries.
No matter how minor you perceive the accident to be, always call 911. The police report is an invaluable piece of evidence for your claim, especially in an "at-fault" state like Georgia. When emergency services arrive, cooperate fully, but avoid speculating about fault or making definitive statements like "I'm fine" if you're not entirely sure. Explain what happened calmly and factually. If paramedics offer to check you out or transport you to a hospital, take them up on it. Getting immediate medical attention is not only crucial for your health but also creates an official record of your injuries, which will be vital for your car accident claim. Many serious injuries, such as whiplash or concussions, don't manifest until hours or even days later, and delaying treatment can weaken your claim significantly.
Gathering Essential Information at the Scene
Once you've ensured everyone's safety and called for help, the next crucial step is to gather as much information as possible from the scene. This can feel like a daunting task when you're shaken, but it's an absolute game-changer when it comes to proving fault and supporting your insurance claim.
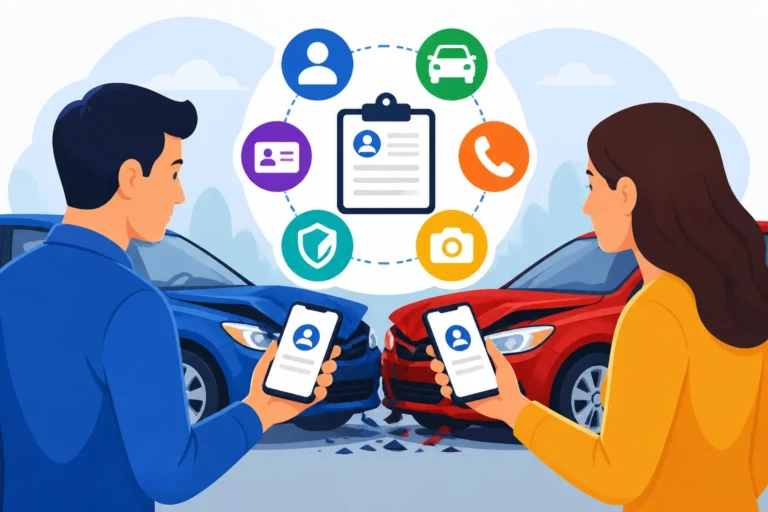
Start by exchanging information with the other driver(s). You'll need their full name, contact information (phone number and email), driver's license number, license plate number, and insurance company name and policy number. Don't forget to get their vehicle information too – make, model, year, and vehicle identification number (VIN) if you can locate it. If there were any witnesses to the accident, politely ask for their names and contact information as well. Their unbiased account can be incredibly valuable if there's a dispute over who was at fault.
Technology is your friend here. Use your smartphone to take copious photographs and videos of the accident scene. Capture the damage to all vehicles involved from multiple angles, skid marks on the road, traffic signs or signals nearby, any debris, and the overall conditions of the road and weather. If your accident happened on a busy Atlanta street like Peachtree Street, or a highway, having photographic evidence of the surrounding environment can provide crucial context. Make sure to photograph the other driver's license plate and insurance card. These visual records serve as irrefutable evidence and can help reconstruct the accident for insurance adjusters and legal professionals.
Understanding Georgia's At-Fault Insurance System
Navigating the aftermath of an accident in Georgia requires a clear understanding of the state's insurance laws. Unlike some other states, Georgia operates under an "at-fault" system, which significantly impacts how your claim proceeds and what you can recover.
How Georgia's Fault System Works
In an "at-fault" state like Georgia, the person who caused the accident (the at-fault driver) is responsible for covering the damages and injuries of the other parties involved. This means that after an accident, you'll generally pursue compensation from the at-fault driver's insurance company. This is a stark contrast to a What Is a No-Fault State? And Which States Are No-Fault where your own insurance would cover certain damages regardless of who caused the collision.
The challenge, of course, lies in determining who is at fault. This isn't always clear-cut, especially in complex scenarios like a T-bone accident at an intersection or a multi-car pileup. Insurance companies will investigate, review police reports, and sometimes even hire accident reconstructionists to establish liability. If you've been in an accident, understanding How Fault Is Determined in a Car Accident is crucial. Georgia law also employs a concept called "modified comparative negligence" with a 50% bar. This means if you are found to be 50% or more responsible for the accident, you cannot recover any damages from the other driver. If you are found to be less than 50% at fault, your recoverable damages will be reduced by your percentage of fault. For instance, if you suffer $10,000 in damages but are found 20% at fault, you would only be able to recover $8,000. This is a vital distinction compared to Modified Comparative Negligence 50% vs 51% Bar rules in other states, where even 50% fault might allow for some recovery.
Types of Insurance Coverage in Georgia
To legally drive in Georgia, motorists are required to carry specific minimum amounts of car insurance coverage. These minimums are in place to ensure that if an accident does occur, there's a financial safety net for those who are injured or whose property is damaged.
The minimum liability coverage required in Georgia is often referred to as 25/50/25:
- $25,000 for bodily injury liability per person: This covers medical expenses, lost wages, and pain and suffering for a single person injured in an accident you cause.
- $50,000 for bodily injury liability per accident: This is the maximum amount your insurance will pay for all injuries in an accident you cause, regardless of how many people are injured.
- $25,000 for property damage liability per accident: This covers the cost to repair or replace another person's property (like their vehicle) if you are at fault for the damage.
It's important to understand that these are just the minimums. In many accidents, especially those involving serious injuries or extensive property damage, these amounts can quickly be exhausted. If the at-fault driver only has minimum coverage and your damages exceed their policy limits, you might face challenges in recovering full compensation. This is where your own optional coverages, like Uninsured/Underinsured Motorist (UM/UIM) coverage, can become incredibly important. UM/UIM coverage protects you if the at-fault driver doesn't have insurance or doesn't have enough insurance to cover your losses. Other optional coverages, such as collision (for damage to your own car regardless of fault) and comprehensive (for non-collision damage like theft or natural disasters), also play a role in your overall financial protection.
Step-by-Step Guide to Filing Your Claim in Georgia
The process of actually filing your claim can feel like navigating a maze, especially when you're still recovering from the shock and physical aftermath of an accident. Knowing the steps can bring some much-needed clarity.
Notifying Your Insurance Company (First-Party Claim)
Even if the accident wasn't your fault, it is almost always a good idea to notify your own insurance company as soon as reasonably possible. Many people hesitate, thinking "Why should I tell my insurance if I didn't cause it?" However, your policy likely has clauses requiring prompt notification, and failing to do so could potentially jeopardize future coverage or assistance. Plus, your own insurer can be a valuable resource.
Your insurance company can guide you on the process, help arrange for a rental car if your policy includes it (Rental Car Reimbursement After an Accident), or assist with getting estimates for your vehicle's damage under your collision coverage, if you have it. If the at-fault driver is uninsured or underinsured, your own Fault in an Uninsured Motorist Accident coverage (if you opted for it) would be triggered. Furthermore, if you carry Medical Payments (MedPay) coverage, your own insurer can help cover your initial medical bills, regardless of fault, providing immediate relief while liability is being sorted out. To get started, you'll need to contact your insurance agent or the company's claims department and provide them with all the information you gathered at the scene. They will typically open a "first-party claim" for your own damages and injuries, which can be run in parallel with a claim against the at-fault driver's policy. For a general overview, it helps to understand How to File a Car Accident Insurance Claim.
Filing a Claim with the At-Fault Driver's Insurance (Third-Party Claim)
This is typically where the main battle for compensation takes place in Georgia's at-fault system. You or your lawyer will file a claim directly with the insurance company of the driver who caused the accident. This is called a "third-party claim" because you are not the policyholder.
The at-fault driver's insurance company will assign a claims adjuster to your case. Their job is to investigate the accident and determine liability and the value of your damages. This process can be lengthy and feel impersonal, and it's essential to approach it strategically. When you first speak with the adjuster, provide only the basic facts of the accident. Avoid making definitive statements about your injuries or the extent of damage, as you might not know the full scope yet. Be particularly cautious if they ask for a recorded statement. While it might seem helpful to provide one, it's often used by the insurance company to find inconsistencies or statements that could minimize their liability. It's often best to consult with a legal professional before giving a recorded statement. Understanding Dealing With Insurance Adjusters After a Car Accident and Do You Have to Give a Recorded Statement? can help you navigate this interaction. You’ll need to provide all the documentation you collected: police report, photos, witness statements, and eventually, medical records and bills.
Documenting Your Damages and Injuries
Thorough documentation is the backbone of any successful car accident claim in Georgia. Without solid proof of your losses, even the most legitimate claim can struggle. This goes far beyond just getting an estimate for your car repair.
You need to meticulously document every single expense and impact related to the accident. For property damage, get detailed repair estimates from reputable body shops. If your vehicle is totaled, the insurer will determine its Actual Cash Value (ACV), but having your own research on comparable sales in Georgia can help if you disagree with their valuation. For injuries, this means keeping a complete record of all medical appointments, treatments, medications, and physical therapy sessions. Every single medical bill, from the ambulance ride to specialist visits, needs to be saved. If you miss work due to your injuries, you'll need documentation of lost wages from your employer, detailing the hours or income you forfeited. How Lost Wages Are Calculated in a Settlement can be a complex area, so clear records are paramount.
Beyond economic damages, which are quantifiable losses like medical bills and lost wages, you'll also be seeking non-economic damages, such as pain and suffering. While these are harder to put a number on, they are very real consequences of an accident. Keep a journal documenting your daily pain levels, emotional distress, limitations on your activities, and how the injuries affect your quality of life. This personal account, alongside your medical records and physician's notes, helps paint a comprehensive picture of your suffering for the insurance company or court. Learning How to Prove Injuries in a Car Accident Claim is essential for strengthening this aspect of your claim.
Common Challenges and What to Expect
Even with all your documentation in order, the claims process can present unexpected hurdles. Knowing what challenges to anticipate can help you prepare and respond effectively.
Dealing with Lowball Offers and Denials
It's a common, and often frustrating, experience: you've been injured, your car is damaged, and you're struggling to recover, only to receive a settlement offer from the insurance company that feels insultingly low. This is not uncommon, and it's a tactic some insurers use to settle cases quickly and cheaply. They might try to downplay your injuries, argue you had pre-existing conditions, or even suggest you were partially at fault to reduce the amount they have to pay.
Don't let a lowball offer discourage you. It's a starting point for negotiation, not the final word. You need to understand your claim's true value, which includes all your current and future medical expenses, lost wages, property damage, and pain and suffering. If you receive an offer that doesn't adequately cover your losses, be prepared to counter it with a well-supported demand. This often involves providing additional evidence of your damages, a detailed account of your pain and suffering, and a clear explanation of why the insurer's offer is insufficient. If the insurance company denies your claim entirely, that's another frustrating scenario. This could happen for various reasons, such as disputing fault, claiming you didn't seek medical attention quickly enough, or alleging policy violations. In such cases, understanding What to Do If an Insurance Company Denies Your Claim is crucial. You'll need to understand the exact reason for the denial and be prepared to appeal it, often with the help of an attorney. The process can feel like a battle, but remember you have rights.
When to Consider Legal Counsel
While you can technically file a car accident claim on your own, especially for very minor incidents with clear fault and no injuries, there are many situations where hiring a car accident lawyer in Georgia is highly advisable.
If you've suffered significant injuries, incurred substantial medical bills, or experienced lost wages, a lawyer can be invaluable. They understand the intricacies of Georgia's fault laws, how to accurately calculate the full scope of your damages (including future medical costs and pain and suffering), and how to negotiate effectively with aggressive insurance adjusters. They can also protect you from making statements that could harm your claim. For instance, if you are unsure about Who Is at Fault When Both Drivers Are to Blame, an attorney can help clarify the situation and protect your interests. Furthermore, if liability is disputed, if the other driver is uninsured or underinsured, or if the insurance company is simply being uncooperative or offering a settlement far below what your claim is worth, a lawyer becomes a powerful advocate. They can gather evidence, interview witnesses, navigate the legal system, and, if necessary, take your case to court.
Another critical factor is the statute of limitations. In Georgia, you generally have two years from the date of the accident to file a personal injury lawsuit. This deadline can vary for property damage or in specific circumstances, so it's vital to be aware of it. Missing this deadline means you forfeit your right to pursue compensation in court. A lawyer will ensure all deadlines are met. For more information, consider reading Do You Need a Lawyer for a Car Accident? and specifically checking Statute of Limitations for Car Accidents in Georgia to understand the precise timeframes applicable to your situation. Engaging an attorney early in the process can significantly streamline your claim, maximize your potential settlement, and allow you to focus on your recovery without the added stress of legal and insurance complexities.
Here's a quick summary of key points for filing a car accident claim in Georgia:
| Step | Key Action | Georgia Specifics |
|---|---|---|
| Immediate Scene | Ensure safety, call 911, exchange info, document. | Police report is crucial. Adrenaline can mask injuries; seek immediate medical attention. |
| Fault System | Understand liability rules. | Georgia is an "at-fault" state. Modified Comparative Negligence (50% bar) applies; if 50% or more at fault, no recovery. |
| Insurance Coverage | Know minimum requirements. | Minimum 25/50/25 liability. Consider UM/UIM for protection against underinsured drivers. |
| Notify Insurer | Inform your own company. | Even if not at fault, notify promptly. Can assist with collision, MedPay, or UM/UIM claims. |
| Third-Party Claim | File with at-fault driver's insurer. | Be cautious with recorded statements. Adjusters will investigate fault and damages. |
| Documentation | Gather all evidence. | Meticulously track medical bills, lost wages, vehicle damage, and pain/suffering. Essential for proving damages. |
| Legal Counsel | Consider a lawyer for serious cases. | Highly recommended for significant injuries, disputed fault, or lowball offers. Protects rights, meets deadlines. |
Disclaimer
The information provided in this article is intended for general informational purposes only and does not constitute legal advice. Car accident claims are highly fact-specific, and the laws governing them can be complex. It is strongly recommended that you consult with a qualified personal injury attorney in Georgia for advice regarding your individual situation. Reliance on any information presented herein is solely at your own risk.