Economic vs Non-Economic Damages Explained
When you're dealing with the aftermath of a car accident, the financial and emotional toll can feel overwhelming. Beyond the immediate shock, trying to understand how you'll be compensated for your losses can be incredibly confusing. This guide aims to clear up one of the most fundamental distinctions in any car accident claim: the difference between economic and non-economic damages, helping you understand what you can claim.
Understanding Car Accident Damages
After a car accident, especially one that wasn't your fault, you're likely to hear the term "damages" quite a bit. It sounds like something lawyers talk about, and while it is a legal term, it's also a very practical concept that directly impacts what you might recover. Essentially, "damages" refer to the financial compensation awarded to an injured party for the losses they've suffered due to someone else's negligence or wrongdoing. These losses can range from the obvious, like a smashed fender or a hospital bill, to the far less tangible, such as the persistent ache in your neck or the fear you now feel every time you get behind the wheel.
Understanding the different types of damages is crucial because it helps you accurately assess the full scope of your losses and ensures you're not leaving any potential compensation on the table. It's not just about covering what's immediately apparent; it's about acknowledging every way the accident has negatively impacted your life, both financially and personally.
What "Damages" Really Mean in a Claim
In the context of a car accident claim, "damages" isn't about damage to your car in the casual sense, but rather the total sum of money sought to make you whole again. The idea is to put you back in the position you would have been in had the accident never occurred. Of course, we know that's not always entirely possible, especially when serious injuries are involved. However, the legal system strives to achieve this through monetary compensation.
These damages encompass a wide range of categories, designed to cover everything from the most straightforward bills to the profound, life-altering changes you might endure. From the moment of impact and beyond, every expense, every missed opportunity, and every bit of suffering becomes a component of your overall damages. Think of it as a comprehensive accounting of every negative consequence stemming from the crash. For a more detailed look at what can be claimed, check out our guide on What Are Damages in a Car Accident Claim?.
The Core Difference: Tangible versus Intangible Losses
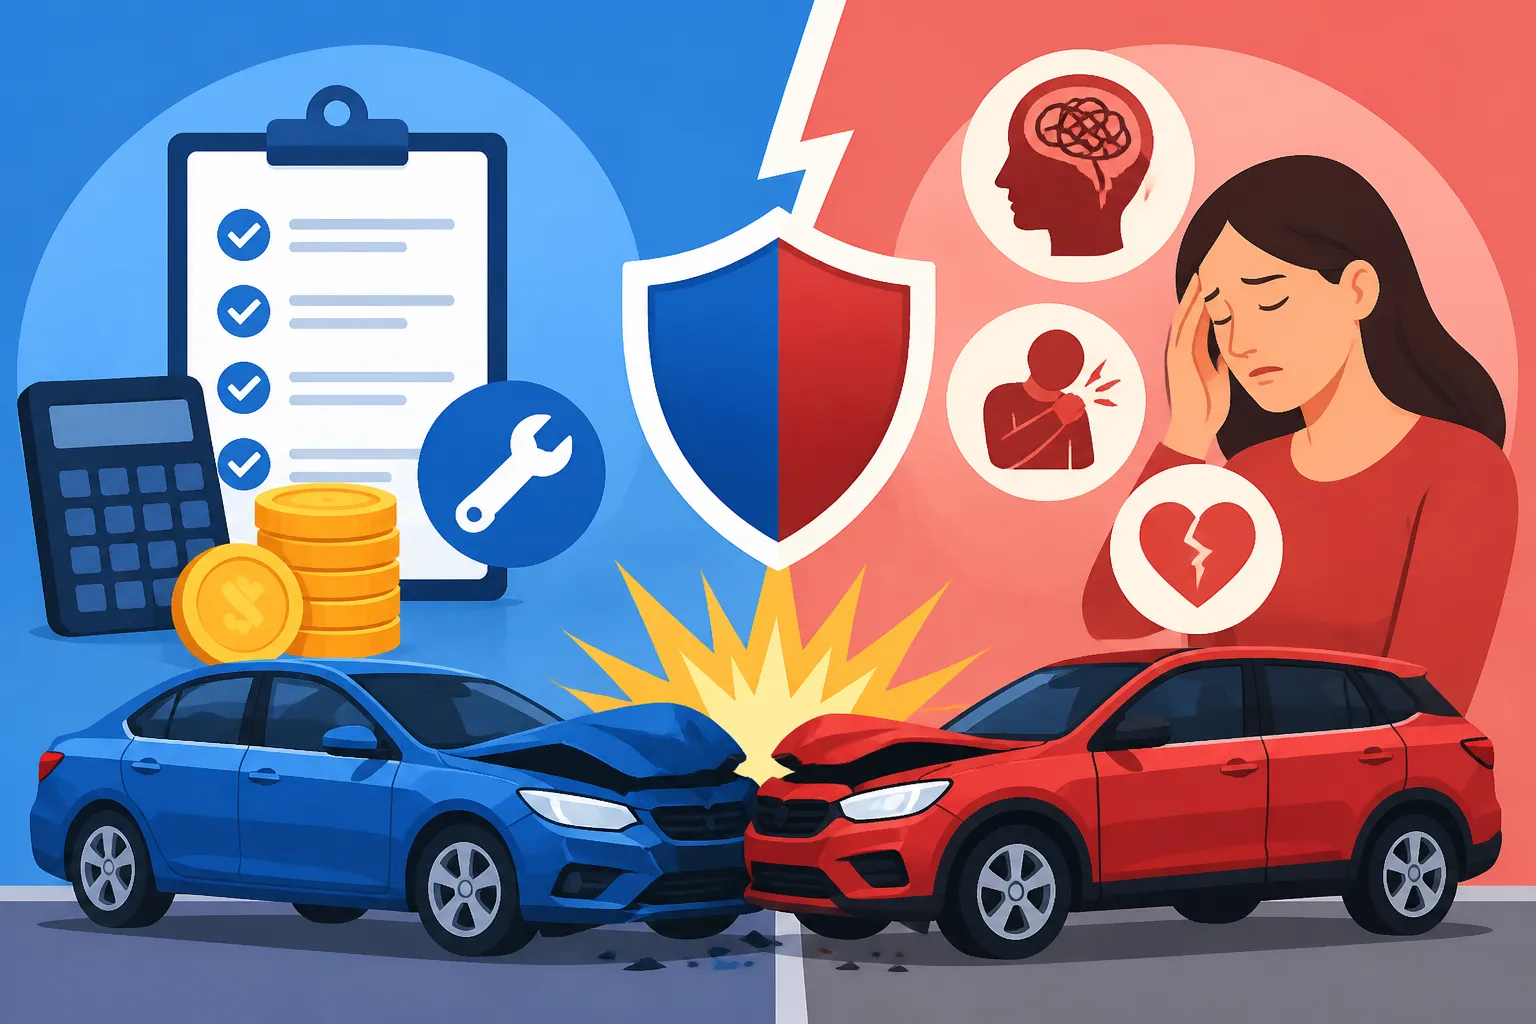
The fundamental distinction between economic and non-economic damages boils down to their nature: are they easily quantifiable with a specific dollar amount, or are they more subjective and harder to put a price tag on?
Economic damages, often referred to as "special damages," are the concrete, verifiable financial losses you've incurred or will incur. These are the expenses you can point to on a receipt, a medical bill, or a pay stub. They are objective and calculable, representing the direct monetary impact of the accident. When you add them up, you get a specific number.
Non-economic damages, sometimes called "general damages," are the intangible, subjective losses that don't come with a bill. These are the personal experiences of suffering, distress, and diminished quality of life caused by the accident. While they don't have a fixed price, they are very real and can profoundly affect your well-being. Assigning a monetary value to these types of losses is often more complex and requires careful consideration. This is a critical distinction, as both types of damages contribute significantly to How Much Is My Car Accident Settlement Worth? (2026).
Diving Deep into Economic Damages
Economic damages are the backbone of most car accident claims because they are relatively straightforward to prove. These are the real-world costs you incur that directly resulted from the accident. Think of them as the "out-of-pocket" expenses, even if insurance or another party eventually covers them. These damages are designed to cover your financial hardship, ensuring you aren't left holding the bag for someone else's mistake.
The goal is to provide a complete picture of all the monetary losses, both immediate and future, that you've faced because of the collision. This often requires diligent record-keeping and a clear understanding of what qualifies.
Medical Bills: More Than Just the ER Visit
When you think about medical bills after an accident, the first thing that often comes to mind is the emergency room visit. And yes, those initial costs are definitely a huge part of economic damages. But it goes far beyond that first trip to the hospital. Medical damages can encompass every single medical expense related to your injuries. This includes ambulance rides, diagnostic tests like X-rays, CT scans, and MRIs, doctor's visits, specialist consultations (orthopedists, neurologists, chiropractors, physical therapists, etc.), prescription medications, and even over-the-counter pain relievers recommended by a doctor.
Furthermore, it also includes future medical expenses. If your injuries require ongoing treatment, rehabilitation, or even potential surgeries years down the line, these anticipated costs are part of your economic damages. This might involve long-term physical therapy for a chronic back injury, future consultations with pain management specialists, or even the cost of adaptive equipment if you suffered a severe spinal injury. Proving these future costs often involves expert medical testimony projecting your long-term needs and associated expenses. Our guide on Common Car Accident Injuries: Complete Guide (2027) delves into many injuries that incur significant medical costs.
Lost Wages and Earning Capacity
Another major component of economic damages is the income you've lost because you couldn't work due to your injuries. This includes the wages, salary, commissions, bonuses, and benefits you missed out on from the day of the accident up until you can return to work, or until your claim is settled. If you're an hourly worker, it might be easier to calculate; if you're a freelancer or work on commission, it can be more complex, requiring tax returns and work records.
Beyond just lost wages, there's also the concept of "loss of earning capacity." This refers to your reduced ability to earn money in the future because of permanent or long-term injuries. For example, if a skilled surgeon suffers a severe hand injury that prevents them from performing surgery ever again, their loss of earning capacity would be substantial, even if they can still work in a different, lower-paying capacity. Calculating this requires economic experts who can project your potential earnings before the accident versus your probable earnings post-accident. Understanding How Lost Wages Are Calculated in a Settlement can be very helpful here.
Property Damage: Repairing or Replacing Your Vehicle
This is often the most immediate and tangible economic damage after a collision. Property damage covers the cost of repairing or replacing your vehicle, whichever is less. If your car can be repaired, you're entitled to the cost of those repairs, including parts and labor. If your car is deemed a "total loss," meaning the cost to repair it exceeds a certain percentage of its actual cash value (ACV), then you're entitled to the ACV of your vehicle immediately before the accident.
Property damage can also extend to other personal items damaged in the crash, such as a laptop, a bicycle rack, car seats, or even items of clothing. Furthermore, rental car expenses while your vehicle is being repaired or replaced are typically included as economic damages. This ensures you're not left without transportation during the recovery period.
Other Out-of-Pocket Expenses
The accident might have triggered a host of other expenses that might not immediately jump out as "damages," but they certainly are. These can be various incidental costs that you wouldn't have incurred if the accident hadn't happened. For instance, if your injuries prevent you from performing household chores, you might need to pay for temporary cleaning services or yard work. If you need assistance with childcare because you're recovering, those costs can be included.
Transportation costs to and from doctor's appointments, physical therapy sessions, or even the pharmacy to pick up prescriptions are also legitimate economic damages. This could mean mileage reimbursement if you use your own car, or the cost of rideshares, taxis, or public transit. Even modifications to your home or vehicle to accommodate a new disability caused by the accident would fall under this category. Every dollar spent that links back to the accident should be documented meticulously.
| Type of Damage | Description | Examples |
|---|---|---|
| Economic | Objective, quantifiable financial losses, easily proven with documentation. | Medical bills, lost wages, property repair/replacement, rental car, household help, transportation for medical care. |
| Non-Economic | Subjective, intangible losses; difficult to assign a direct monetary value. | Pain and suffering, emotional distress, loss of enjoyment of life, disfigurement, inconvenience, loss of consortium. |
Exploring Non-Economic Damages
While economic damages are about the calculable financial hit, non-economic damages address the much deeper, personal impact an accident can have. These are the costs that don't show up on a bill, but they profoundly affect your daily life and overall well-being. Insurance companies and courts recognize that an injury isn't just about the physical recovery; it's also about the emotional and psychological toll it takes.
Understanding and articulating these non-economic losses is often the most challenging aspect of a personal injury claim, but it's vital for securing fair compensation. These damages are about acknowledging the suffering and changed quality of life that can occur.
Pain and Suffering: The Invisible Burden
This is perhaps the most commonly recognized non-economic damage, yet it's often the most misunderstood. "Pain and suffering" refers to the physical pain, discomfort, and agony you experience because of your injuries. This isn't just the pain you feel immediately after the crash, but also the chronic pain, recurring headaches, stiffness, or discomfort that might persist for weeks, months, or even years. It also includes the mental anguish associated with these physical symptoms.
Imagine someone who loved hiking every weekend but now suffers from a debilitating knee injury, making even a short walk painful. Their physical pain is clear, but the frustration, sadness, and loss of a cherished activity are part of their suffering. These are the moments of discomfort during rehabilitation, the sleepless nights due to aching joints, or the simple inability to sit comfortably. It's the daily reminder of the accident that manifests as physical discomfort. For a deeper dive into how these are valued, consider reading Pain and Suffering: How It's Calculated.
Emotional Distress and Mental Anguish
Beyond physical pain, car accidents can leave deep emotional and psychological scars. Emotional distress and mental anguish cover the negative emotional responses to the accident and your injuries. This can manifest in many ways: anxiety, fear, depression, anger, frustration, and even post-traumatic stress disorder (PTSD). Many accident victims report a profound fear of driving or being a passenger, leading to isolation or significant lifestyle changes.
For example, a driver involved in a severe collision might develop panic attacks when passing the accident site or struggle with nightmares related to the crash. They might withdraw from social activities, lose interest in hobbies, or experience increased irritability. These are not minor inconveniences; they can significantly impair a person's quality of life and often require professional counseling or therapy to manage. Documenting these impacts, perhaps through a journal or therapist's notes, is crucial to proving their extent.
Loss of Enjoyment of Life
This damage category speaks to the reduction in your ability to enjoy the activities and hobbies that brought you pleasure and fulfillment before the accident. It's about how your injuries have robbed you of your quality of life. Maybe you were an avid runner, a talented musician, a dedicated gardener, or a parent who loved playing actively with your children. If your injuries prevent you from engaging in these activities, or significantly diminish your capacity to enjoy them, that loss is a compensable damage.
Consider a person who adored gardening but now finds bending and kneeling impossible due to a back injury. Or a cyclist who can no longer ride their bike because of a permanent arm injury. These losses go beyond mere inconvenience; they represent a significant diminishment of their former lifestyle and personal happiness. This category truly captures the essence of how an accident can fundamentally change who you are and what you can do.
Disfigurement and Permanent Impairment
Some accidents result in injuries that lead to permanent changes in appearance or function, and these are clearly non-economic damages. Disfigurement refers to any permanent alteration to your physical appearance, such as scarring, burns, loss of a limb, or facial deformities. These types of injuries can cause significant emotional trauma, self-consciousness, and psychological distress, affecting your confidence and social interactions for the rest of your life.
Permanent impairment, on the other hand, refers to a lasting reduction in a bodily function. This could be a limited range of motion in a joint, chronic weakness, nerve damage that causes numbness or tingling, or partial paralysis. These impairments can affect your ability to perform daily tasks, work, or engage in recreational activities. While there might be economic components to these (like future medical care or lost earning capacity), the fundamental loss of a fully functioning body and the emotional impact of living with a permanent physical change are non-economic. When looking at Average Car Accident Settlement Amounts by Injury, you'll often see these types of severe, lasting injuries leading to higher non-economic compensation.
How Damages Are Calculated and Proved
This is where the rubber meets the road. Identifying your losses is one thing; successfully proving them and putting a dollar value on them for an insurance company or a jury is quite another. While economic damages rely heavily on documentation, non-economic damages require a more nuanced approach, often involving compelling narratives and expert opinions. The process of calculating and proving damages is a critical step in How Car Accident Settlements Are Calculated.
Documenting Economic Losses
Proving economic damages is all about the paper trail. Every medical bill, every prescription receipt, every pay stub, and every repair estimate becomes a piece of evidence. It's crucial to keep meticulous records from the moment the accident occurs. This means holding onto all medical records, including bills, invoices, hospital statements, and records from every doctor, therapist, or specialist you see. Don't forget pharmacy receipts for medications.
For lost wages, gather pay stubs, W-2s, tax returns, and a letter from your employer confirming missed workdays and salary. If you're self-employed, profit and loss statements, bank records, and client invoices will be essential. Property damage requires repair estimates, photographs of the damage, and documentation of your vehicle's value if it's totaled. Keep records of any out-of-pocket expenses like transportation, childcare, or household help. The more thoroughly you document everything, the stronger your case for economic recovery.
Valuing Non-Economic Damages
This is often the trickiest part of a car accident claim because there isn't a direct bill for "pain and suffering." However, there are established methods used by insurance companies and legal professionals to arrive at a fair value. One common approach involves a "multiplier" method. This takes the total economic damages and multiplies them by a factor, usually between 1.5 and 5, depending on the severity of your injuries, the duration of your recovery, and the impact on your life. More severe, permanent, or debilitating injuries would warrant a higher multiplier.
Another method is the "per diem" approach, where a daily rate is assigned for each day you experience pain and suffering, typically from the date of the accident until you reach maximum medical improvement (MMI). However, these are just starting points. The real value comes from your ability to articulate and demonstrate the impact of your suffering. This means providing detailed accounts of your daily struggles, how your injuries prevent you from doing things you once enjoyed, and how your emotional well-being has been affected. This is also where your medical records, therapist notes, and even testimony from friends and family about changes in your demeanor or abilities become incredibly important.
The Role of Evidence and Expert Testimony
To effectively prove both economic and non-economic damages, robust evidence is indispensable. For economic damages, the evidence is largely documentary – the stack of bills, pay stubs, and receipts you've so carefully collected. For non-economic damages, while medical records showing the severity of injury are vital, other forms of evidence are critical too. This includes personal journals detailing your daily pain levels and emotional state, photographs of injuries (especially those showing disfigurement or the healing process), and even testimony from your medical providers.
Expert testimony often plays a significant role, particularly in cases involving serious injuries or complex financial losses. Medical experts can testify about the nature and extent of your injuries, your prognosis, and your future medical needs. Vocational experts can assess how your injuries impact your ability to work and your future earning capacity. Economic experts can then quantify those lost earnings and future medical costs into a precise financial figure. Without proper evidence and, at times, expert corroboration, it can be incredibly difficult to How to Prove Injuries in a Car Accident Claim to an insurance adjuster or a court.
The Impact of State Laws and Insurance
The legal landscape surrounding car accident claims isn't uniform across the United States. State laws play a significant role in how damages are calculated and what you can ultimately recover. Understanding these nuances is crucial, as they can directly influence the value of your economic and non-economic damages. The type of insurance system your state follows, and even the degree of your own fault in an accident, can dramatically alter your potential settlement.
Comparative Fault and Damage Reduction
One of the most important factors that can affect your damages is the concept of comparative or contributory negligence. Most states operate under some form of comparative negligence. This means that if you are found to be partially at fault for the accident, your total damages award will be reduced by your percentage of fault. For example, if you are awarded $100,000 in total damages but are found to be 20% at fault, your final payout would be reduced by $20,000, leaving you with $80,000.
There are different variations of comparative negligence, such as "pure comparative negligence," where you can recover damages even if you are mostly at fault (e.g., 90% at fault, you still get 10% of damages), and "modified comparative negligence" (which can have a 50% or 51% bar), where you cannot recover any damages if your fault exceeds a certain threshold. A few states still follow "contributory negligence," which is very harsh, barring you from any recovery if you are found even 1% at fault. This aspect is incredibly important to understand, especially when considering What Happens If You're Partially at Fault?.
No-Fault versus At-Fault Systems
The type of insurance system in your state also dictates how you initially claim certain damages. In an "at-fault" or "tort" state, the driver who caused the accident is responsible for all damages, and you typically file a claim with their insurance company (a third-party claim) for both economic and non-economic damages.
In a "no-fault" state, regardless of who caused the accident, each driver first turns to their own insurance company to cover their initial medical expenses and lost wages, up to a certain limit, through their Personal Injury Protection (PIP) coverage. In these states, you can only step outside the no-fault system and sue the at-fault driver for non-economic damages (like pain and suffering) if your injuries meet a certain "serious injury threshold," which varies by state. This threshold might be defined by the severity of the injury, the cost of medical treatment, or a specific duration of disability. Our article What Is a No-Fault State? (And Which States Are No-Fault) explains this in much greater detail.
Insurance Coverage and Limits
Ultimately, the amount of damages you can actually recover is often limited by the available insurance coverage. The at-fault driver's liability insurance policy will have limits for both bodily injury and property damage. If your total damages exceed these policy limits, collecting the full amount can become challenging. In such cases, you might need to pursue a claim directly against the at-fault driver's personal assets (though this is rare and often difficult), or you might turn to your own uninsured/underinsured motorist (UM/UIM) coverage if you have it.
It's also important to remember that insurance companies are businesses. They will always try to minimize payouts. They will scrutinize your medical records, question your pain levels, and potentially dispute your lost wages. This is why having comprehensive documentation and understanding the types of damages you're claiming is so vital in any negotiation or potential lawsuit. The amount of your settlement will directly relate to the available coverage and your ability to prove your losses effectively.
Why This Distinction Matters for Your Claim
Understanding the difference between economic and non-economic damages isn't just academic; it has very real, practical implications for how you approach your car accident claim, negotiate with insurance companies, and ultimately, how much compensation you receive. Failing to recognize or properly document either type of damage can lead to a significantly undervalued settlement, leaving you to bear the financial and personal burdens of someone else's negligence.
Negotiation Strategies
When you enter negotiations with an insurance adjuster, they will initially focus on the easily quantifiable economic damages because these are facts they can verify. They might offer to cover your medical bills and lost wages. However, if you only focus on these, you're missing a huge piece of the puzzle. A robust negotiation strategy involves clearly presenting both your economic and non-economic losses.
For example, when discussing a whiplash injury, you'll present your chiropractor bills and physical therapy costs (economic). But you'll also describe the persistent headaches, the inability to sleep soundly, the difficulty playing with your children, and the constant discomfort that prevented you from focusing at work (non-economic). By detailing how these intangible losses have impacted your daily life, you strengthen your argument for a higher overall settlement. Insurance companies often have formulas they use to estimate non-economic damages based on economic damages, so maximizing your documented economic losses can also indirectly increase your non-economic offers. To learn more about this, check out our guide on How to Negotiate a Car Accident Settlement.
Maximizing Your Compensation
To truly maximize your car accident settlement, you must meticulously account for every single loss, whether it comes with a receipt or not. This means diligently tracking all medical appointments, therapy sessions, medication costs, and lost workdays for your economic damages. But it also means keeping a pain journal, documenting your emotional struggles, and noting every instance where your injuries prevented you from enjoying life's activities for your non-economic damages.
Often, the non-economic component represents a significant portion of a car accident settlement, particularly in cases involving severe or long-lasting injuries. Failing to effectively communicate and prove these intangible losses can mean leaving a substantial amount of money on the table. It's about painting a complete picture of how the accident has affected every aspect of your life, not just your bank account. By doing so, you ensure that the compensation you receive truly reflects the full scope of your suffering and inconvenience. This comprehensive approach is key to securing fair value, as detailed in our comprehensive guide How Much Is My Car Accident Settlement Worth? (2026).
Disclaimer
Please remember that this article provides general informational guidance and is not a substitute for professional legal advice. Car accident claims are complex and highly dependent on the specific facts of your case and the laws of your state. You should consult with a qualified attorney to discuss your individual situation and legal options.