How to File a Car Accident Claim in Pennsylvania
Experiencing a car accident in Pennsylvania is jarring, stressful, and often confusing, especially when you're trying to figure out what to do next. The thought of dealing with insurance companies, paperwork, and potentially medical appointments can feel overwhelming when you're already shaken up. This comprehensive guide is here to walk you through the specifics of filing a car accident claim in the Keystone State, from the moment of impact to understanding the nuances of Pennsylvania's unique insurance laws.
Understanding Pennsylvania's No-Fault System
Pennsylvania operates under a "choice no-fault" insurance system, which can be a real head-scratcher for many drivers. It’s not quite a pure no-fault state, nor is it a traditional at-fault state; it's a blend that can significantly impact how you file a claim and recover damages after an accident. This system was designed to streamline minor injury claims by allowing you to recover medical expenses from your own insurer, regardless of who caused the accident. However, it also introduces complexities, especially when it comes to seeking compensation for pain and suffering.
What "No-Fault" Really Means for You
In Pennsylvania's no-fault system, the primary benefit is that your initial medical bills are typically paid by your own car insurance policy, specifically through your Personal Injury Protection (PIP) coverage, regardless of who was at fault for the accident. This is a crucial distinction from traditional "at-fault" states, where the at-fault driver's insurance would cover these costs from the get-go. The idea is to reduce litigation for less severe injuries and ensure quick access to medical care without waiting for fault to be officially determined.
However, this doesn't mean fault is irrelevant. While your own insurance pays for your medical treatment, establishing fault is still vital for property damage claims and for seeking compensation for non-economic damages, like pain and suffering, if your injuries meet certain thresholds. It's a common misconception that "no-fault" means no one is ever held responsible, but that's simply not true, particularly for more serious accidents. Understanding What Is a No-Fault State? (And Which States Are No-Fault) can shed more light on the general principles.
Navigating Your Own Insurance Coverage (PIP)
Your Personal Injury Protection (PIP) coverage is the cornerstone of Pennsylvania's no-fault system for medical expenses. When you purchase car insurance in Pennsylvania, you choose a minimum amount of PIP coverage, usually $5,000, but many drivers opt for higher limits. This coverage pays for your medical treatment, rehabilitation expenses, and sometimes even lost wages, up to your policy limit, regardless of whose fault the accident was.
If your medical expenses exceed your PIP limits, that's when things get more complicated, and you might need to pursue a claim against the at-fault driver's insurance, depending on your tort selection. It's a good idea to review your policy annually and understand exactly what your PIP covers and its limits. Sometimes, drivers find out too late that their basic PIP coverage isn't enough for the full extent of their injuries, which adds another layer of financial stress during an already difficult time.
The Limited Tort vs. Full Tort Option
This is perhaps the most critical decision Pennsylvania drivers make when purchasing car insurance, and it directly impacts your ability to recover non-economic damages, like pain and suffering, after an accident.
With Limited Tort coverage, you agree to a lower insurance premium. In exchange, you give up your right to sue an at-fault driver for pain and suffering damages unless your injuries meet a "serious injury" threshold. This threshold is generally defined as death, serious impairment of a body function, or permanent serious disfigurement. For many common injuries like whiplash or soft tissue damage, proving a "serious injury" under limited tort can be a significant hurdle. This option is popular because it saves money upfront, but it can severely limit your recovery options if you're seriously hurt in a crash.
Choosing Full Tort coverage means you pay a slightly higher premium, but in return, you retain your unrestricted right to sue an at-fault driver for all types of damages, including pain and suffering, no matter how minor or severe your injuries are. This option provides much more flexibility and potential for recovery if you're injured due to someone else's negligence. Many drivers, regrettably, only learn about the implications of their tort selection after an accident has already occurred, discovering they’re constrained by their initial choice.
Here's a quick comparison to illustrate the difference:
| Feature | Limited Tort | Full Tort |
|---|---|---|
| Premium Cost | Generally lower | Generally higher |
| Right to Sue for P&S | Restricted (only for "serious injury") | Unrestricted |
| Medical Expenses | Covered by own PIP (up to limits) | Covered by own PIP (up to limits) |
| Lost Wages | Covered by own PIP (if purchased) | Covered by own PIP (if purchased) |
| Property Damage | Can claim against at-fault driver's insurance | Can claim against at-fault driver's insurance |
| Impact on Claim Value | Significantly lower without "serious injury" | Higher potential for comprehensive recovery |
Understanding these options is vital when you're involved in a collision, as it dictates much of your potential financial recovery for injuries.
Immediate Steps After a Car Accident in Pennsylvania
The moments immediately following a car accident are often chaotic and frightening. However, what you do right after the crash can significantly impact the success of your insurance claim later on. Staying calm, prioritizing safety, and documenting everything are critical first steps. These actions provide essential evidence and protect your rights within Pennsylvania's legal framework. For a general guide on what to do, you can refer to What to Do After a Car Accident: Step-by-Step (2027).
Prioritizing Safety and Calling for Help
Your safety and the safety of others should always be your top concern. If possible and safe to do so, move your vehicle to the side of the road or out of active traffic lanes. Turn on your hazard lights. If anyone is injured, or if the vehicles are severely damaged, immediately call 911. Even for seemingly minor accidents, it's often wise to call the police in Pennsylvania, especially if there's any dispute over fault or if injuries are suspected. The police report can be invaluable for your claim, as it provides an objective account of the incident.
When emergency services arrive, cooperate fully, but avoid admitting fault or making speculative statements about the accident's cause. Stick to the facts. If you're feeling pain, even if it seems minor, report it to the paramedics or police. Sometimes, serious injuries like whiplash or concussions have delayed symptoms, and getting a medical assessment right away is always the safest bet. It's a frustrating reality that sometimes the adrenaline masks the immediate pain, only for it to appear hours or days later.
Documenting the Scene Thoroughly
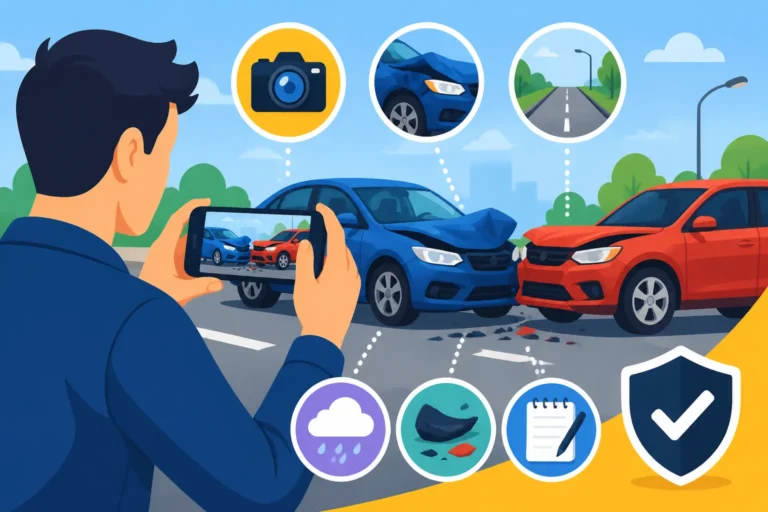
Once safety is secured, start gathering evidence. This is perhaps the most powerful tool you have to support your claim. Take photos and videos with your phone of the accident scene from multiple angles: damage to all vehicles, skid marks, road conditions, traffic signs, any debris, and the surrounding area. Get pictures of the other driver's license plate and insurance card.
Collect contact information from all parties involved, including names, phone numbers, email addresses, and insurance company details. Don't forget any witnesses – their statements can be incredibly helpful. Make notes about the time, date, and location of the accident, as well as weather conditions. The more detailed your documentation, the stronger your position when you How to File a Car Accident Insurance Claim. This detailed record provides concrete facts that can prevent insurance companies from minimizing the incident or shifting blame.
Reporting the Accident to Authorities and Your Insurer
In Pennsylvania, you are generally required to report accidents to the police if there are injuries, fatalities, or if the damage to any vehicle is severe enough that it cannot be driven from the scene. Even for less severe accidents, a police report can be crucial for an insurance claim. Within five days of the accident, you must also report it to your insurance company. This is a critical step, even if you don't believe you were at fault. Delaying this notification can sometimes jeopardize your coverage.
When you contact your insurer, provide them with the basic facts: date, time, location, and the other driver's information. Again, avoid speculating about fault or detailing your injuries until you've been medically evaluated. Let them know you'll provide more details as you gather them. Your insurance company will open a claim and assign an adjuster. It's important to remember that while your adjuster is there to help process your claim, their ultimate goal is to protect the company's bottom line.
Filing Your Insurance Claim in Pennsylvania
After the immediate aftermath, the real work of filing your claim begins. This process involves multiple communications, gathering specific documents, and understanding who you'll be dealing with. Pennsylvania's no-fault system means your first claim will often be with your own insurance for medical bills, even if someone else was clearly at fault for the collision.
Notifying Your Insurance Company
As mentioned, reporting the accident to your own insurance company promptly is non-negotiable in Pennsylvania, usually within five days. You'll need to provide them with the basic details of the accident. They will assign a claims adjuster who will guide you through the initial steps. This adjuster will primarily focus on your PIP coverage for medical expenses and potentially your collision coverage for vehicle damage if you have it.
Your insurer will likely ask you to provide a recorded statement. While you should cooperate, it’s often advisable to consult with an attorney before giving a detailed statement, especially if injuries are involved. Be factual and concise, but avoid guessing or admitting fault. Focus on providing information about your vehicle damage and your medical treatment. This is also where you'll initiate your claim for Common Car Accident Injuries: Complete Guide (2027), making sure all medical visits and diagnoses are clearly documented.
Dealing with the At-Fault Driver's Insurer (if applicable)
If you chose full tort coverage, or if your injuries meet Pennsylvania's "serious injury" threshold under limited tort, you can pursue a claim against the at-fault driver's insurance for non-economic damages like pain and suffering, as well as any medical expenses that exceed your PIP coverage. This is often referred to as a third-party claim. Dealing with the other driver's insurance can be challenging because their adjuster represents their client, the at-fault driver, and their primary goal is to minimize their company's payout.
When communicating with the at-fault driver's insurer, be cautious. You are not obligated to give them a recorded statement. Any information you provide could potentially be used against you to reduce the value of your claim. It's usually best to direct them to your attorney if you have one, or to state that you will provide documentation in writing. They might try to get you to settle quickly, especially if your injuries don't seem severe at first glance. However, it's crucial not to rush into a settlement before you fully understand the extent of your injuries and all your potential damages. Learning how Dealing With Insurance Adjusters After a Car Accident can be very beneficial.
Gathering Essential Documentation
To support your claim, you'll need a comprehensive collection of documents. This includes:
- Police Report: Provides an official account of the accident, often including preliminary fault determination.
- Medical Records and Bills: Every single visit, diagnosis, treatment, prescription, and therapy session related to your injuries. This proves the severity and necessity of your treatment. It's vital for How to Prove Injuries in a Car Accident Claim.
- Wage Loss Documentation: Pay stubs, employer statements, and tax returns if you missed work due to your injuries.
- Vehicle Repair Estimates or Total Loss Declaration: Documentation of the damage to your car and the cost to repair or replace it.
- Photos and Videos: Visual evidence from the scene and of your injuries.
- Witness Statements: Contact information and any written or recorded statements from people who saw the accident.
- Correspondence: Keep detailed records of all communications with insurance companies, medical providers, and any attorneys.
Organizing these documents systematically will make the claims process much smoother and provide a clear picture of your damages. This evidence is what will ultimately help determine How Much Is My Car Accident Settlement Worth? (2026).
What to Expect During the Claims Process in Pennsylvania
The car accident claims process in Pennsylvania can be a marathon, not a sprint. It involves investigations, assessments, negotiations, and sometimes, a bit of a waiting game. Understanding these phases can help manage expectations and reduce the stress of the unknown.
Investigation and Damage Assessment
Once your claim is filed, both your insurance company (for PIP and collision) and potentially the at-fault driver's insurer (for liability and non-economic damages) will begin their investigations. This usually involves:
- Vehicle Inspection: An adjuster will inspect your damaged vehicle to assess the extent of the damage and provide an estimate for repairs. If your vehicle is totaled, they will determine its actual cash value.
- Medical Record Review: For injury claims, the insurance companies will request your medical records. Be aware that they might scrutinize these records to look for inconsistencies, pre-existing conditions, or gaps in treatment that they can use to minimize your claim.
- Accident Reconstruction (in complex cases): For severe accidents or those with disputed liability, accident reconstruction specialists might be brought in to analyze the scene, vehicle damage, and other evidence to determine How Fault Is Determined in a Car Accident.
- Statement Collection: They will review police reports, witness statements, and any statements given by the drivers involved.
This investigative phase can feel invasive and slow, but it's a necessary part of the process. Maintain open communication, but always be mindful of what information you're sharing.
Understanding Settlement Offers and Negotiations
Once the investigation is complete and you've reached maximum medical improvement (MMI) – meaning your doctors believe your condition has stabilized as much as it's going to – the insurance company will typically extend a settlement offer. This initial offer is often low and designed to test your knowledge and resolve. Don't be surprised or insulted; it's a common tactic.
Your role, or your attorney's role, is to counter their offer with a demand letter that outlines all your damages, including medical bills, lost wages, property damage, and pain and suffering. This starts the negotiation process. The amount of your settlement for injuries will depend heavily on the severity of your injuries, the medical treatment you've received, your chosen tort option, and Average Car Accident Settlement Amounts by Injury. If you have limited tort, remember you'll need to demonstrate a "serious injury" to recover pain and suffering.
Negotiations can go back and forth for weeks or even months. It requires patience and a clear understanding of what your claim is genuinely worth. If you feel the offers are unfairly low, you don't have to accept them. Sometimes, the threat of litigation is enough to encourage a more reasonable offer. It's a frustrating dance, but one that is often necessary to get fair compensation.
When to Consider Legal Counsel
While you can technically file a car accident claim on your own in Pennsylvania, there are many situations where hiring a car accident lawyer is highly advisable. This is especially true if:
- You've sustained significant injuries: Serious injuries involve complex medical bills, potential long-term care, and substantial pain and suffering claims, which are difficult to quantify on your own.
- Fault is disputed: If the other driver or their insurance company is trying to shift blame to you, an attorney can help gather evidence and establish the other party's negligence. Understanding What Happens If the Other Driver Blames You? is crucial here.
- You have limited tort coverage but believe you have a "serious injury": Proving a "serious injury" to bypass the limited tort threshold is a legal challenge that often requires expert legal assistance.
- The insurance company is being uncooperative or making lowball offers: Attorneys are adept at negotiating with insurance companies and know how to push for fair compensation.
- Your medical expenses exceed your PIP limits: An attorney can help you pursue additional compensation from the at-fault driver.
- You are unsure about the How Long Do You Have to File a Car Accident Claim?: The statute of limitations for personal injury claims in Pennsylvania is generally two years from the date of the accident, but exceptions exist, and an attorney can clarify.
A personal injury lawyer familiar with Pennsylvania law can navigate the complexities of the no-fault system, deal with insurance adjusters, gather evidence, and fight for the full compensation you deserve. They understand the nuances of the "serious injury" threshold and how to present your case effectively. Many operate on a contingency fee basis, meaning you don't pay unless they win your case, which makes legal representation accessible even if you're facing financial strain after an accident. This makes the question of Do You Need a Lawyer for a Car Accident? (2027) a vital consideration for many.
Disclaimer
Please remember that the information provided in this article is for general informational purposes only and does not constitute legal advice. Car accident claims are complex, and laws can change. You should consult with a qualified legal professional for advice tailored to your specific situation in Pennsylvania.