What to Do If Hit by an Uninsured Driver in Illinois
Getting into a car accident is a truly jarring experience, but finding out the other driver doesn't have insurance can turn that stressful situation into an outright nightmare. You're left wondering how you're supposed to cover the repairs, medical bills, and all the other expenses that pile up. This guide is here to walk you through exactly what steps to take if you find yourself in Illinois, hit by a driver who, unfortunately, is uninsured, helping you navigate the complex world of claims and recovery.
Understanding Uninsured Motorist Coverage in Illinois
Let's face it, nobody wants to think about being hit by a driver without insurance, but it's a very real concern, especially in a bustling state like Illinois. The good news is that Illinois law actually anticipates this problem, and it mandates that all drivers carry a certain level of uninsured motorist (UM) and underinsured motorist (UIM) coverage as part of their liability policies. This is your first line of defense, a crucial safety net.
What Uninsured Motorist (UM) Coverage Does
Uninsured Motorist (UM) coverage is specifically designed to protect you, your passengers, and your vehicle if you're involved in an accident with a driver who either has no car insurance at all or whose insurance company denies coverage or is otherwise unidentifiable (like in a hit-and-run, which we'll talk about later). Think of it as your own insurance company stepping in to pay for damages that the at-fault, uninsured driver should have paid. This can include your medical expenses, lost wages, and even pain and suffering.
For example, if you're cruising down I-55 near Springfield and someone swerves into your lane, causing a collision, and then you discover they don't have insurance, your UM coverage would kick in. It's essentially your policy doing double duty to cover what the other driver’s non-existent insurance should have handled. In Illinois, the minimum UM bodily injury limits are usually $25,000 per person and $50,000 per accident. It's often highly recommended to carry more than the minimum if you can, given how quickly medical bills and lost income can accumulate.
What Underinsured Motorist (UIM) Coverage Does
While UM coverage deals with drivers who have no insurance, Underinsured Motorist (UIM) coverage addresses those situations where the at-fault driver does have insurance, but their policy limits aren't enough to cover the full extent of your damages. This happens more often than you might think, especially with severe injuries or expensive vehicle repairs.
Imagine a scenario where a driver with only the state minimum liability coverage of $25,000 hits your brand-new SUV in downtown Chicago, causing $30,000 worth of damage and leading to $40,000 in medical bills for your whiplash and a broken arm. Their $25,000 policy would be quickly exhausted. That extra $45,000 in damages? That's where your UIM coverage steps in to cover the difference, up to your UIM policy limits. It picks up where the other driver's insufficient coverage leaves off. Both UM and UIM are critical components of a robust auto insurance policy in Illinois.
Immediate Steps After an Accident with an Uninsured Driver
Being involved in any accident is disorienting, but the added layer of an uninsured driver can make you feel even more helpless. However, the initial steps you take at the scene are crucial for protecting your rights and ensuring you have the evidence needed for a successful claim later. Do not skip these, even if you’re stressed or upset.
Ensuring Safety and Calling the Police
First and foremost, your safety and the safety of others should be your priority. Move your vehicle to a safe location if possible, away from active traffic. Turn on your hazard lights. Even if the accident seems minor, it's always wise to call the police, especially when an uninsured driver is involved. In Illinois, if an accident results in injury, death, or property damage exceeding $1,500 (or $500 if the vehicle is uninsured), you are legally required to report it. Even if the damage is less, a police report creates an official record of the incident and identifies all parties involved, including the critical detail that the other driver is uninsured.
When the police arrive, they will create a police report that includes details like the date, time, location, parties involved, and a preliminary assessment of fault. This report can be incredibly helpful later when you're working on your claim. The police can also verify the other driver's insurance status, or lack thereof. Sometimes, a driver might claim to be uninsured when they actually are, or vice-versa, but the police can often confirm this. For more on this, check out our guide on Police Reports and Car Accident Fault.
Gathering Evidence and Information
This step is critical, perhaps even more so when the other driver lacks insurance. Since you won't be dealing with their insurer, every piece of evidence you collect will bolster your claim with your own insurance company.
- Exchange Information: Get the other driver's full name, address, phone number, driver's license number, and license plate number. Even if they claim to have no insurance, ask for their insurance information anyway – sometimes people are mistaken or deliberately misrepresent their status.
- Witness Information: If there are any witnesses, politely ask for their names and contact information. An objective third-party account can be incredibly valuable.
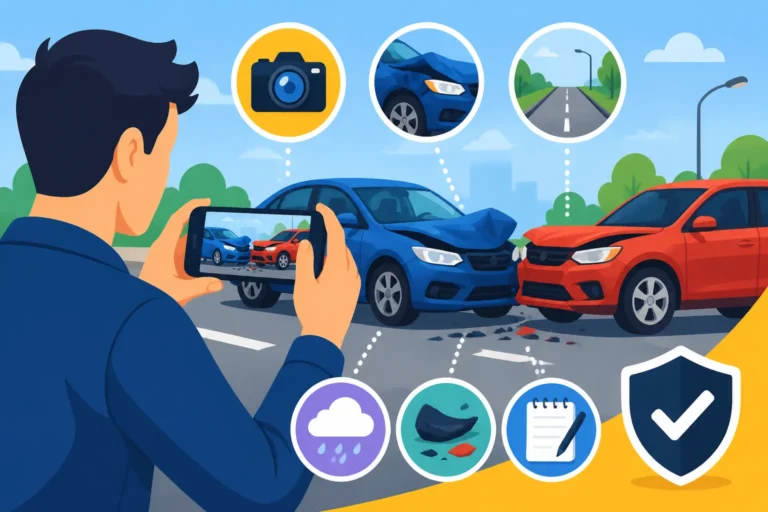
- Take Photos and Videos: Use your phone to document everything. Take pictures of:
- Both vehicles from multiple angles, showing the extent of the damage.
- The accident scene, including road conditions, traffic signs, and any skid marks.
- License plates of all vehicles involved.
- Any visible injuries on yourself or passengers.
- The other driver's license and any paperwork they might have.
- Notes: Write down everything you remember about the accident while it's fresh in your mind. This includes the date, time, weather conditions, how the accident occurred, and any statements made by the other driver.
Collecting comprehensive evidence helps to prove How Fault Is Determined in a Car Accident, which is essential even when filing with your own UM policy.
Seeking Medical Attention Promptly
Even if you feel fine right after the accident, it's always a good idea to seek medical attention. Adrenaline can mask pain, and some injuries, like whiplash or concussions, might not manifest symptoms for hours or even days. Visiting a doctor ensures that any injuries are properly diagnosed and documented, which is crucial for your claim. This is especially true since your UM coverage will pay for these medical expenses.
A gap in medical treatment can be used by insurance companies to argue that your injuries weren't caused by the accident. Make sure to follow all medical advice, attend follow-up appointments, and keep detailed records of all your treatments, medications, and expenses. Our Common Car Accident Injuries: Complete Guide (2026) can give you an idea of what to look out for.
Filing Your Uninsured Motorist Claim in Illinois
Once you've handled the immediate aftermath, the next big step is to actually file your claim. This process can feel daunting, but it's where your mandatory UM/UIM coverage truly shines. Remember, you're now dealing with your own insurance company, which can sometimes be a slightly smoother path than battling an at-fault driver's insurer, though challenges can still arise.
Notifying Your Insurance Company
As soon as possible after the accident, you need to notify your own insurance company. Even if the accident wasn't your fault, calling your insurer is a critical step, especially when the other driver is uninsured. They need to be aware of the incident to activate your UM coverage. Be honest and factual when you explain what happened. Provide them with all the information you collected at the scene, including the police report number if available.
When you call, you'll likely speak with a representative who will open a claim file for you. They will assign an adjuster to your case. This adjuster is responsible for investigating the claim and working with you to determine the appropriate payout under your policy. This is a situation where you should definitely Should You Call Your Insurance If It Wasn't Your Fault?—the answer is a resounding yes!
Working with Your Insurance Adjuster
Your insurance adjuster will be your main point of contact throughout the claims process. They will review the evidence, speak to witnesses (if any), and evaluate your damages. Be prepared to provide them with:
- Police Report: The official record of the accident.
- Photos and Videos: Visual evidence of the damage and scene.
- Medical Records: Documentation of your injuries, treatments, and prognosis.
- Lost Wage Documentation: If you missed work due to your injuries.
- Repair Estimates: For your vehicle damage.
While your adjuster works for your insurance company, their goal is still to settle the claim for the lowest possible amount. It's important to be cooperative but also firm. Provide them with all requested documentation in a timely manner, but avoid giving a recorded statement without understanding your rights. For a deeper dive, check out our guide on Dealing With Insurance Adjusters After a Car Accident.
Documenting and Proving Your Damages
Proving your damages to your own insurance company for a UM claim is very similar to how you would prove damages in a third-party claim. You need solid documentation for everything you're claiming.
- Medical Expenses: Keep all receipts, bills, and explanation of benefits (EOB) statements from your health insurance. You need to link your injuries directly to the accident. Your medical records from doctors, physical therapists, chiropractors, and specialists will be vital. Our article on How to Prove Injuries in a Car Accident Claim provides comprehensive advice on this.
- Lost Wages: If your injuries prevented you from working, you can claim lost income. Provide pay stubs, employment verification, and a doctor's note stating your inability to work.
- Property Damage: Obtain at least two independent repair estimates for your vehicle. If your car is totaled, your insurer will determine its actual cash value (ACV).
- Pain and Suffering: While harder to quantify, you can claim pain and suffering under your UM policy. This includes physical discomfort, emotional distress, and loss of enjoyment of life. Keeping a daily journal of your pain levels, limitations, and emotional state can help support this aspect of your claim.
Here's a quick overview of what your UM/UIM coverage typically does and doesn't cover:
| Category | Uninsured/Underinsured Motorist (UM/UIM) Coverage | Standard Liability Coverage (for the at-fault driver) |
|---|---|---|
| Bodily Injury | Covers your medical bills, lost wages, pain and suffering if the at-fault driver is uninsured or underinsured. | Covers the other driver's (your) medical bills, lost wages, and pain and suffering if you are at fault. |
| Property Damage | In Illinois, UM usually only covers bodily injury. Separate collision coverage or UM Property Damage (UMPD) is needed for vehicle repairs. | Covers damage to the other driver's (your) vehicle if you are at fault. |
| Hit-and-Run | Often covers bodily injury and sometimes property damage if the at-fault driver cannot be identified. | Not applicable, as no other driver's information is available. |
| Deductible | May have a deductible, especially for UMPD or if your BI claim is for property damage. | No deductible for the claimant; the at-fault driver pays theirs if filing on their own collision. |
| Mandatory in IL | Yes (UM Bodily Injury), UIM offered as optional. | Yes (Bodily Injury & Property Damage). |
What if You Don't Agree with the Settlement Offer?
It’s not uncommon for insurance companies to make an initial offer that feels low. Don't feel pressured to accept it immediately. You have the right to negotiate. Gather any additional documentation that supports your higher valuation, such as new medical bills, a detailed prognosis from your doctor, or a strong argument for your pain and suffering.
If negotiations with your insurance company reach an impasse, you have a few options:
- Arbitration: Many UM/UIM policies include an arbitration clause, meaning you and your insurer can agree to have a neutral third party resolve the dispute. This is often less formal and less expensive than a lawsuit.
- Mediation: Similar to arbitration, but the mediator helps facilitate a compromise rather than making a binding decision.
- Lawsuit: As a last resort, you can file a lawsuit against your own insurance company to compel them to pay the benefits under your UM/UIM policy. This should be considered carefully, as it can be a lengthy and costly process. Consulting with a personal injury attorney can provide clarity on your options and the potential strength of your case.
Remember, patience and thorough documentation are your best friends in this process. Our guide on How to File a Car Accident Insurance Claim offers more general tips applicable here.
What Happens if You Don't Have Uninsured Motorist Coverage?
While Illinois mandates UM bodily injury coverage, it's possible some drivers might choose to carry only the bare minimum or, unfortunately, let their policy lapse. If you're hit by an uninsured driver and you don't have active UM coverage yourself, the situation becomes significantly more challenging. It’s a frustrating position to be in, and it's why understanding your options, however limited, is so important.
Paying Out of Pocket or Through Health Insurance
Without UM coverage, covering your medical expenses and vehicle repairs can fall entirely on your shoulders.
- Medical Expenses: Your health insurance policy would become your primary coverage for accident-related injuries. However, you'd still be responsible for your deductibles, co-pays, and any expenses not covered by your health plan. If you don't have health insurance, you could be looking at significant out-of-pocket medical bills, potentially leading to medical liens.
- Vehicle Damage: For your car repairs, if you have collision coverage on your own policy, that would kick in to cover the damage. You would, however, have to pay your deductible. If you don't have collision coverage, then you're generally stuck paying for the repairs yourself. This can be a huge financial burden for many families in Illinois.
It's a stark reminder of why carrying comprehensive auto insurance, including adequate UM/UIM and collision coverage, is so vital. It protects your finances against the irresponsible actions of others on the road.
Pursuing the At-Fault Uninsured Driver Directly
Technically, you always have the right to pursue the at-fault uninsured driver directly for damages through a personal injury lawsuit. However, this path comes with significant hurdles and is often not a practical solution.
- Limited Assets: The primary reason a driver is uninsured is often financial. They might not have the assets or income to pay for your damages, even if a court orders them to. Winning a judgment in court is one thing; actually collecting that money is another entirely. You could end up with a piece of paper (a judgment) that is essentially worthless.
- Time and Expense: Filing a lawsuit can be a lengthy and expensive process. You'd need to hire an attorney, pay court fees, and go through discovery and potentially a trial. If the other driver truly has no assets, you could spend a lot of time and money only to come up empty-handed.
- Difficulty Locating/Serving: Sometimes, uninsured drivers are difficult to locate, especially if they provide incomplete or false information at the scene. This can further complicate any attempt to sue them.
While it's an option, pursuing an uninsured driver directly usually isn't the most efficient or effective way to recover your losses. It's often recommended to exhaust all options through your own insurance first, as that is where your most reliable recovery source lies. If you find yourself in this truly tough spot, speaking with an attorney is even more crucial to understand the slim possibilities available to you.
What If It Was a Hit-and-Run in Illinois?
A hit-and-run accident is particularly frustrating because the at-fault driver flees the scene, leaving you without any contact or insurance information. This scenario can leave you feeling abandoned and hopeless, but your UM coverage often extends to cover these incidents as well, providing a much-needed safety net.
Uninsured Motorist Coverage and Hit-and-Run
In Illinois, your Uninsured Motorist (UM) bodily injury coverage generally applies to hit-and-run accidents. This means your own insurance company would cover your medical expenses, lost wages, and pain and suffering, just as if you had identified the uninsured driver. This is a huge relief for many people, as the idea of having to pay for everything out of pocket after being victimized by a hit-and-run driver is truly terrifying.
For your vehicle damage, if you have collision coverage, that would cover the repairs to your car, subject to your deductible. Some policies might also include Uninsured Motorist Property Damage (UMPD) coverage, which would cover your vehicle repairs after a hit-and-run, sometimes with a lower deductible than standard collision coverage. It’s important to review your specific policy documents or speak with your insurance agent to understand how your coverage applies to hit-and-run situations. When you're making your initial report, ensure you emphasize that it was a hit-and-run.
The Importance of a Police Report and Evidence
Even though the other driver fled, reporting a hit-and-run to the police immediately is paramount. The police report serves as official documentation that the incident occurred and that the other driver is unidentified. Without a police report, your insurance company might be skeptical of your claim or even deny it, arguing there's no proof of a collision with an uninsured (or unidentified) vehicle.
Beyond the police report, gather any evidence you possibly can:
- Witness Statements: Did anyone see the accident or the car that fled? Their contact information and observations are invaluable.
- Surveillance Footage: Are there nearby businesses, traffic cameras, or even doorbell cameras that might have captured the incident? This could potentially help identify the fleeing vehicle.
- Vehicle Debris: Any paint chips, broken plastic, or shattered glass left at the scene from the other vehicle can sometimes provide clues.
- Damage Assessment: Document the damage to your own vehicle meticulously.
Even small details can sometimes help law enforcement or your insurance company piece together what happened. The more information you can provide, the stronger your hit-and-run claim will be. Filing a claim after a hit-and-run is slightly different than a standard claim, and our guide on What to Do After a Hit-and-Run provides more detailed steps.
Navigating the Legal and Financial Ramifications
Dealing with the aftermath of an accident with an uninsured driver isn't just about repairs and medical bills; it also involves understanding the legal and financial landscape. Illinois is an "at-fault" state, meaning the person who caused the accident is responsible for the damages. When that person is uninsured, your UM coverage steps in to essentially fulfill that "at-fault" driver's financial responsibility.
Potential Increase in Insurance Premiums
One common concern when filing any claim, even a UM claim where you're not at fault, is whether your insurance premiums will increase. Generally, in Illinois, if you file an uninsured motorist claim and you are demonstrably not at fault for the accident, your premiums should not increase solely because of that claim. Illinois law protects policyholders from premium increases for accidents that are not their fault.
However, insurance companies look at many factors when determining premiums, and a history of claims, even not-at-fault claims, can sometimes indirectly influence rates over time. It's a complicated calculation. If you're concerned about a potential increase, it's a good idea to discuss this with your insurance agent directly or shop around for new quotes if you notice a significant hike. They should be able to clarify their specific policies regarding UM claims.
When to Consider Legal Counsel
While you might be able to handle a straightforward UM claim on your own, there are several situations where hiring a car accident attorney can be immensely beneficial:
- Serious Injuries: If you've sustained significant injuries requiring extensive medical treatment, long recovery times, or resulting in permanent disability, an attorney can help ensure you receive full compensation for current and future medical expenses, lost earning capacity, and substantial pain and suffering. They can also help you understand How Much Is My Car Accident Settlement Worth? (2026)
- Disputed Liability: Even with an uninsured driver, your own insurance company might try to argue you were partially at fault. An attorney can help investigate and prove the other driver's sole fault.
- Lowball Settlement Offers: If your insurance company offers a settlement that doesn't adequately cover your damages, an attorney can negotiate on your behalf to achieve a fair settlement.
- Complex Policies or Denials: If your policy has unusual clauses, or if your insurance company denies your claim outright, a lawyer can navigate the complexities and fight for your rights.
- Hit-and-Run with Disputes: If there are complications in proving a hit-and-run or if the insurer is hesitant to cover it, legal counsel can be crucial.
- Multiple Parties or Complex Scenarios: If more than two vehicles were involved, or if there are other complicating factors, an attorney can help sort through the legal mess.
Even if you're just unsure, many personal injury attorneys in Illinois offer free initial consultations. It costs you nothing to discuss your situation and get an expert opinion on whether legal representation would benefit your case. This is especially true if you're navigating the complexities of What Happens If You're Partially at Fault? or if your claim is taking longer than expected. It’s always good to be informed.
Disclaimer
Please remember that this guide provides general information about dealing with an uninsured driver in Illinois and should not be considered legal advice. Every accident and insurance policy is unique. It is highly recommended to consult with a qualified attorney or your insurance agent to discuss the specifics of your situation. Laws and insurance regulations can change, and individual circumstances will always impact the best course of action.