What Is a No-Fault State? (And Which States Are No-Fault)
Navigating the aftermath of a car accident is already stressful, but trying to understand who pays for what, especially when different states have different rules about "fault," can feel like deciphering ancient hieroglyphs. Many people get confused about whether their state is a "no-fault" state and what that actually means for their ability to get their medical bills paid and their car fixed. This comprehensive guide is here to demystify no-fault insurance, explain how it works, list which states operate under this system, and help you understand your options if you find yourself in a crash.
Understanding the Core Concept of No-Fault Insurance
When a car accident happens, one of the first questions people instinctively ask is, "Who was at fault?" In most parts of the country, this question is absolutely central to how insurance claims and injury compensation are handled. However, in "no-fault" states, the initial approach to getting your immediate medical expenses and lost wages covered changes dramatically. It's a system designed to streamline basic benefits, reduce litigation for minor injuries, and ensure accident victims receive prompt care.
How No-Fault Systems Differ from At-Fault Systems
The fundamental difference between a no-fault system and an at-fault (or "tort") system lies in how your insurance benefits are accessed immediately after a collision, especially concerning personal injuries. In an at-fault state, like California or Texas, the driver who caused the accident is generally responsible for all damages, including medical bills, lost wages, and property damage, incurred by the other parties. This means if you're hit by another driver, you typically file a claim with their insurance company, and their liability coverage is expected to pay for your damages. The whole process hinges on proving who was negligent, a concept often explored in guides like Who Is at Fault in a Car Accident? Complete Guide (2027).
On the other hand, in a no-fault state, regardless of who caused the accident, your own insurance policy's Personal Injury Protection (PIP) coverage is designed to pay for your medical expenses and a portion of your lost wages up to a certain limit. This happens without waiting for an official "fault" determination. Imagine you're driving in Florida and get rear-ended. Instead of immediately going after the other driver's insurance for your doctor's visit, you'd turn to your own PIP coverage first. This doesn't mean fault is irrelevant entirely, but its role is significantly minimized for initial injury claims. Property damage, however, almost always remains an at-fault claim, even in no-fault states.
The Rationale Behind No-Fault Laws
So, why did some states adopt this seemingly counter-intuitive system? The primary goal behind no-fault insurance was to reduce the number of minor injury lawsuits flooding the courts and to ensure accident victims could get immediate medical treatment without lengthy delays while fault was being debated. Think about it: in a traditional at-fault system, if you have a soft tissue injury like whiplash, you might have to wait for weeks or months for the other driver's insurance to accept liability before you can get reimbursed for your physical therapy bills. This could leave you in pain and struggling financially.
No-fault systems aimed to solve this by creating a direct path to benefits from your own insurer, speeding up the process and theoretically lowering overall legal costs for minor claims. The idea was to create a more efficient system for minor injuries, allowing accident victims to focus on recovery rather than on a drawn-out battle over blame. It was also believed to potentially lower insurance premiums by reducing litigation, though whether it has achieved this universally is a subject of ongoing debate among consumers and industry experts.
What No-Fault Really Means for Your Car Accident Claim
The term "no-fault" can be a bit misleading because it doesn't mean nobody is responsible for the accident. It simply changes the initial mechanism for claiming certain benefits. Understanding this distinction is crucial to navigating a car accident claim in one of these states. Your claim process will likely look quite different from what someone in an at-fault state experiences.
Personal Injury Protection PIP Coverage: Your Primary Benefit
The cornerstone of any no-fault system is Personal Injury Protection (PIP) coverage. This is a mandatory component of auto insurance in no-fault states, and it's designed to pay for your medical expenses, a percentage of lost wages, and sometimes even essential services (like if you need help with household tasks because of your injuries) resulting from a car accident, regardless of who caused the collision.
Let's say you're in a fender bender in Massachusetts, a no-fault state. You might experience some neck stiffness later that day. With PIP coverage, you can seek immediate medical attention, and your own insurance will cover those bills up to your policy's limit. This can be incredibly helpful for getting prompt care, which is often vital for recovery, especially for injuries like whiplash. PIP coverage essentially acts as a first line of defense, ensuring you aren't stuck waiting for an adjuster to decide fault before you can see a doctor. This coverage also typically extends to passengers in your vehicle and sometimes even household members who are injured as pedestrians or cyclists. Knowing What to Do After a Car Accident: Step-by-Step (2027) is still paramount, as gathering information and seeking medical attention remains crucial.
The Threshold for Suing an At-Fault Driver
While PIP handles initial expenses, no-fault doesn't completely eliminate the ability to sue the at-fault driver. Instead, it establishes a "threshold" that must be met before you can step outside the no-fault system and pursue a personal injury lawsuit against the negligent party for damages like pain and suffering. This threshold is usually defined in one of two ways:
- Monetary Threshold: This means your medical bills must exceed a certain dollar amount (e.g., $5,000 in medical expenses) before you can sue.
- Verbal Threshold: This is often more complex and requires that your injury be "serious" or "permanent" as defined by state law. Examples might include significant disfigurement, permanent loss of a bodily function, a fractured bone, or wrongful death.
If your injuries meet or exceed your state's specific threshold, you can then pursue a lawsuit against the at-fault driver for non-economic damages, such as pain and suffering, and any economic damages that exceed your PIP limits. This is where concepts like Economic vs Non-Economic Damages in Injury Claims become extremely important. Until that threshold is met, the no-fault system generally limits your ability to seek these types of compensation from the other driver.
Property Damage Claims in No-Fault States
Here's an important point that often surprises people: even in no-fault states, property damage claims almost always operate under traditional at-fault rules. This means if someone else hits your car and damages it, their property damage liability insurance is responsible for paying for the repairs or the total loss value of your vehicle.
So, while your PIP coverage will handle your bodily injuries regardless of fault, you'll still pursue a claim against the at-fault driver's insurance for the damage to your car. If the other driver is uninsured, or if you were at fault, you would rely on your own collision coverage (if you have it) to pay for your vehicle repairs. This dual system can be confusing, as it means you might be dealing with your own insurer for your medical bills and the other driver's insurer for your car's damages simultaneously. It's a key detail when considering How to File a Car Accident Insurance Claim.
A Comprehensive List of No-Fault States
It's not as simple as dividing states into "no-fault" and "at-fault" boxes, as some states offer a choice or have hybrid systems. Knowing your state's specific laws is paramount. The list of no-fault states can sometimes shift or be interpreted differently based on the specifics of their insurance requirements.
States with Pure No-Fault Systems
In pure no-fault states, all drivers are generally required to carry Personal Injury Protection (PIP) coverage, and you must file an injury claim with your own insurer first, regardless of who caused the accident. You cannot sue the at-fault driver for pain and suffering unless your injuries meet a specific "threshold" defined by state law.
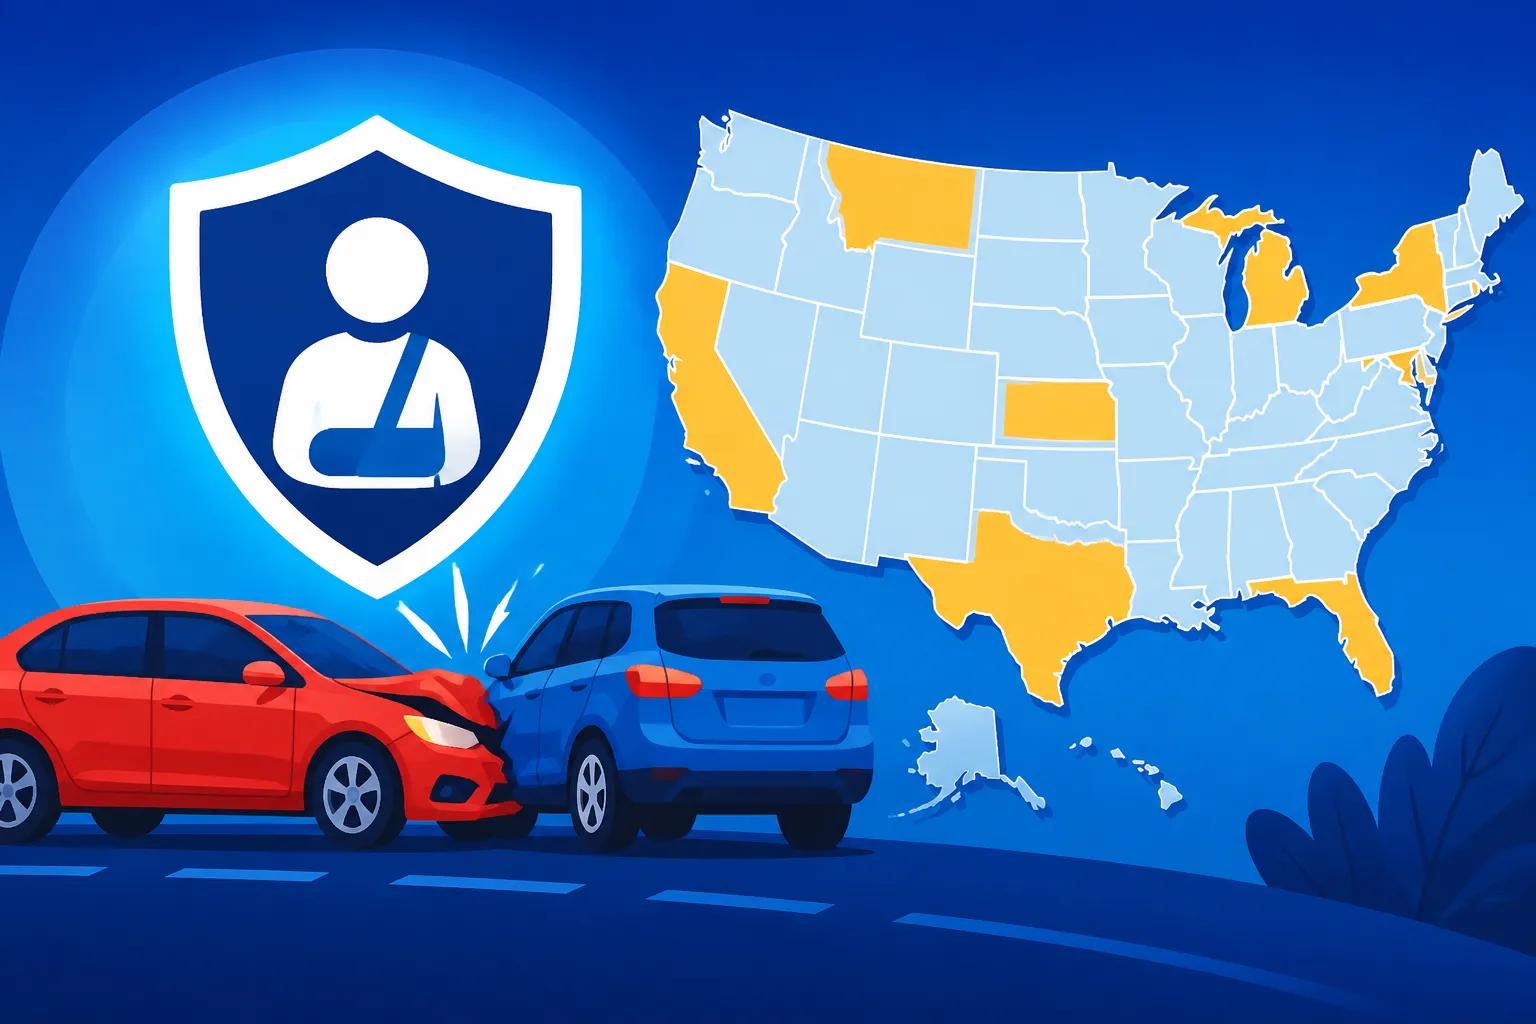
The following states primarily operate under a pure no-fault system:
- Florida: Drivers must carry a minimum of $10,000 in PIP coverage. Florida is one of the strictest no-fault states.
- Hawaii: PIP is mandatory, and there's a serious injury threshold for seeking additional damages.
- Kansas: Requires PIP coverage with specific limits for medical expenses, lost income, and more.
- Kentucky: Unique in that it's a "choice" no-fault state, but those who don't opt out are considered pure no-fault.
- Massachusetts: Drivers are required to carry PIP, and there's a verbal and monetary threshold for tort claims.
- Michigan: Historically one of the most comprehensive no-fault systems, though reforms have introduced more options and limits. PIP benefits used to be unlimited for medical expenses but now have chosen limits.
- Minnesota: Mandates PIP coverage to cover medical expenses and lost wages.
- New Jersey: Another "choice" no-fault state where drivers typically select a no-fault option.
- New York: Requires PIP coverage, often referred to as "basic economic loss" benefits, with a serious injury threshold for lawsuits.
- North Dakota: PIP benefits are mandatory for basic economic losses.
- Pennsylvania: Another "choice" no-fault state, allowing drivers to choose between full tort (at-fault) or limited tort (no-fault).
- Utah: PIP coverage is required for medical care and lost wages.
These states have laws specifically designed to prioritize each driver's own insurance for their immediate injury needs. For instance, if you're in an accident in Florida, your first stop for medical bills is your own PIP, not the other driver's bodily injury liability.
States with Choice No-Fault Options
Some states offer drivers a "choice" between a no-fault system and a traditional at-fault system when they purchase their car insurance. This means you might be able to opt out of the no-fault system entirely and retain your right to sue for any injury, even minor ones, directly against the at-fault driver. However, choosing this option usually means you also give up some of the immediate benefits of PIP.
- Kentucky: Drivers can reject the no-fault system and choose to be bound by tort liability, meaning they can sue or be sued for any amount. If they don't explicitly reject it, they default to no-fault.
- New Jersey: Offers a "limited tort" option (no-fault) and a "full tort" option (at-fault). Limited tort generally means you can't sue for pain and suffering unless you meet the verbal threshold.
- Pennsylvania: Similar to New Jersey, offering "limited tort" (no-fault for pain and suffering unless threshold met) and "full tort" (retains full right to sue).
These "choice" states can add another layer of complexity, as the rules for your claim could depend not only on where the accident happened but also on the specific insurance policy choices made by both you and the other drivers involved.
States That Are Not No-Fault (At-Fault or Tort States)
The vast majority of states operate under an "at-fault" or "tort" system. In these states, the person deemed responsible for causing the accident is financially liable for all damages, including bodily injury and property damage, incurred by the victims. There's no PIP coverage that pays out regardless of fault for injuries, though medical payments (MedPay) coverage or uninsured motorist bodily injury (UMBI) coverage can provide similar immediate benefits if you have them.
Here's a list of states that are not no-fault:
- Alabama
- Alaska
- Arizona
- Arkansas
- California
- Colorado
- Connecticut
- Delaware
- Georgia
- Idaho
- Illinois
- Indiana
- Iowa
- Louisiana
- Maine
- Maryland
- Mississippi
- Missouri
- Montana
- Nebraska
- Nevada
- New Hampshire
- New Mexico
- North Carolina
- Ohio
- Oklahoma
- Oregon (requires specific first-party benefits, sometimes confused with PIP, but is an at-fault state)
- Rhode Island
- South Carolina
- South Dakota
- Tennessee
- Texas
- Vermont
- Virginia
- Washington
- West Virginia
- Wisconsin
- Wyoming
In these states, determining How Fault Is Determined in a Car Accident is crucial. If you're involved in a crash in one of these states, your ability to recover damages for your injuries and property will largely depend on proving the other driver's negligence. This often means working with their insurance company, which can sometimes be a contentious process, especially if What Happens If the Other Driver Blames You? arises.
Here's a quick reference table for easier understanding:
| System Type | Description | Key States |
|---|---|---|
| Pure No-Fault | Your own insurance (PIP) pays for your medical bills and lost wages regardless of fault. You can only sue the at-fault driver for pain and suffering if injuries meet a "threshold." Property damage is usually still at-fault. | Florida, Hawaii, Kansas, Massachusetts, Michigan, Minnesota, New York, North Dakota, Utah |
| Choice No-Fault | Drivers can choose between a no-fault system (limited tort) or an at-fault system (full tort) when purchasing insurance. Your choice determines your rights to sue for non-economic damages. | Kentucky, New Jersey, Pennsylvania |
| At-Fault (Tort) | The driver who caused the accident is responsible for all damages (injuries and property damage) to other parties. You typically file a claim against their liability insurance. No statewide PIP for all injury claims regardless of fault. | Alabama, California, Texas, Illinois, Ohio, Virginia, Washington, Arizona, Tennessee, Maryland, Colorado, and all other states not listed above as no-fault or choice no-fault. |
It's important to remember that laws can change, so always verify the current regulations for your specific state or consult with a legal professional or your insurance provider if you have questions.
The Pros and Cons of No-Fault Insurance
Like any complex legal and insurance system, no-fault insurance comes with its own set of advantages and disadvantages. What one person sees as a benefit, another might view as a serious drawback. Understanding both sides can help you grasp why this system exists and how it might impact you.
Potential Advantages for Accident Victims
For individuals involved in car accidents, especially minor ones, the no-fault system was designed with several benefits in mind.
First and foremost, prompt medical treatment and financial relief are often cited as the biggest advantages. When you're injured, your immediate concern is getting care and making sure you don't go bankrupt in the process. With PIP, you don't have to wait for the insurance companies to investigate, assign fault, and accept liability. Your own insurer steps in quickly to cover your initial medical bills and a portion of your lost wages, allowing you to focus on healing without the added stress of financial uncertainty. This is a huge comfort, especially for injuries that require ongoing therapy or time off work.
Secondly, no-fault systems aim to reduce litigation for minor accidents. Since you can't sue for pain and suffering unless you meet a specific threshold, many smaller claims are handled entirely through PIP. This means fewer cases clogging up the court system and theoretically, a faster resolution for your basic economic losses. For many people, avoiding a potentially lengthy and stressful lawsuit, as detailed in articles like How Long Does a Car Accident Settlement Take?, is a welcome relief.
Finally, in some instances, no-fault can lead to lower overall insurance costs for drivers, though this is a heavily debated point. The idea is that by reducing the number of lawsuits and the associated legal fees, insurance companies save money, which can then be passed on to policyholders. However, the cost of extensive PIP benefits can sometimes offset these savings, leading to varying results state by state.
Common Criticisms and Disadvantages
Despite its intended benefits, no-fault insurance faces significant criticism and can present distinct disadvantages for accident victims.
A major complaint is the limitation on recovering non-economic damages, particularly pain and suffering. If your injuries don't meet your state's "threshold" – whether it's a monetary amount or a definition of "serious injury" – you cannot sue the at-fault driver for the emotional distress, discomfort, and loss of enjoyment of life that your injuries caused. This can feel incredibly unfair if you've suffered significant, long-lasting pain that doesn't quite cross the legal threshold for a lawsuit. Imagine suffering chronic back pain after a crash in a no-fault state, but because you didn't break a bone, you can't pursue a claim for your suffering. This can lead to frustration and a feeling that justice hasn't been served. Guides on Pain and Suffering: How It's Calculated highlight the significant value these damages can represent in at-fault states.
Another disadvantage is the potential for higher insurance premiums due to the mandatory nature and sometimes generous limits of PIP coverage. While it aims to reduce litigation, the cost of paying out claims regardless of fault can sometimes drive up the baseline cost of insurance for everyone in the state. Drivers in Michigan, for example, have historically faced some of the highest auto insurance premiums in the nation, partly due to its generous no-fault benefits.
Furthermore, no-fault systems can sometimes fail to deter reckless driving. If drivers know that victims will primarily claim from their own insurance, there might be less of a direct financial consequence for their negligent actions, at least immediately after the accident. While premium increases still occur for at-fault drivers, the immediate impact on the victim's ability to claim against them for full damages is reduced.
Finally, the system can be complex and confusing for the average person. Dealing with your own insurer for injuries and the other driver's insurer for property damage, all while trying to understand thresholds and legal options, can be a headache. This often leads people to wonder, Do You Need a Lawyer for a Car Accident? (2027) even in seemingly simple cases.
Navigating a Car Accident in a No-Fault State
Getting into a car accident is disorienting, no matter where you are. But in a no-fault state, your initial steps and subsequent claim process will have some unique considerations. Knowing what to do in the immediate aftermath can make a significant difference in how smoothly your claim proceeds and whether you can recover all the compensation you're entitled to.
Immediate Steps After an Accident
The first moments after a collision are crucial, regardless of your state's fault laws. Your priority should always be safety and documenting the scene.
- Ensure Safety: Move your vehicle to a safe location if possible, turn on your hazard lights, and check for injuries.
- Call the Police: Even in a minor accident, it's often wise to call the police, especially if there are injuries or significant property damage. A police report can be invaluable for insurance claims. For more details on police involvement, see Police Reports and Car Accident Fault.
- Exchange Information: Get the other driver's name, contact information, insurance details, and license plate number. Also, collect witness contact information if anyone saw the crash.
- Document the Scene: Take photos and videos of the vehicles, the accident location, road conditions, and any visible injuries. The more evidence you have, the better.
- Seek Medical Attention: This is absolutely critical in a no-fault state. Even if you feel fine, some injuries have delayed symptoms. Get checked out by a doctor as soon as possible after the accident. Remember, your PIP coverage is designed to cover these initial medical costs, so utilize it. Documenting your injuries immediately helps establish a clear link between the accident and your physical harm. Common injuries like whiplash often appear hours or even days later.
- Report to Your Insurer: Notify your own insurance company about the accident promptly. This is important for initiating your PIP claim.
Filing Your Personal Injury Protection PIP Claim
Once you've taken care of immediate safety and medical needs, filing your PIP claim with your own insurance company is the next crucial step.
Your insurer will likely provide you with the necessary forms to fill out. These forms will typically ask for details about the accident, your injuries, and information about your medical providers. Make sure to be thorough and accurate. Submit all medical bills and records related to your injuries to your PIP carrier. Keep detailed records of all communications with your insurance company, including dates, times, and the names of representatives you speak with.
Remember, PIP is your primary source of payment for medical treatment and lost wages up to your policy limits, regardless of who caused the crash. The process for Dealing With Insurance Adjusters After a Car Accident can still be tricky, even with your own insurer, so be prepared to provide all documentation requested efficiently.
When You Can Step Outside the No-Fault System
If your injuries are severe and meet your state's "threshold," you then have the option to pursue a personal injury claim against the at-fault driver. This means you can sue them for damages not covered by your PIP, most notably pain and suffering, and potentially other economic losses that exceed your PIP limits.
This is where proving fault becomes paramount again, just like in an at-fault state. You'll need to demonstrate the other driver's negligence caused the accident and that their actions led to your qualifying injuries. This often involves collecting further evidence, witness statements, accident reconstruction, and expert medical testimony to substantiate the severity of your injuries. For insights into this process, reviewing How to Prove the Other Driver Was at Fault can be highly beneficial. If you reach this stage, it's almost always advisable to consult with an experienced personal injury attorney who understands the nuances of your state's no-fault laws and how to successfully navigate a tort claim.
Personal Injury Protection PIP Explained in Detail
Since Personal Injury Protection (PIP) is the cornerstone of any no-fault system, understanding its intricacies is essential. It's more than just coverage for medical bills; it’s a comprehensive benefit designed to get you back on your feet after a crash. However, what it covers and its limitations can vary significantly from one state to another.
What PIP Covers: Medical Expenses, Lost Wages, and More
PIP coverage is designed to provide "economic loss" benefits to you and your passengers after a car accident, regardless of who caused it. The specific categories and amounts covered depend on your state's laws and your chosen policy limits, but generally, PIP includes:
- Medical Expenses: This is the most common and often the largest component. PIP pays for reasonable and necessary medical treatment for accident-related injuries. This can include ambulance rides, emergency room visits, hospital stays, doctor's appointments, prescription medications, physical therapy, chiropractic care, and sometimes even dental work or psychological counseling if related to the accident.
- Lost Wages/Income Continuation: If your injuries prevent you from working, PIP can reimburse a percentage of your lost income. This is typically not 100% of your wages but a specified percentage, often around 80% in many states, up to a certain weekly or monthly limit. There might also be a waiting period before these benefits kick in.
- Essential Services/Replacement Services: If your injuries prevent you from performing routine household tasks like cleaning, cooking, or childcare, PIP may cover the cost of hiring someone to perform these "essential services" for you, up to a daily or weekly limit.
- Funeral Expenses: In the tragic event of a fatality, PIP often includes a benefit to cover funeral and burial expenses, up to a certain limit.
- Rehabilitation Costs: Long-term rehabilitation, assistive devices, or modifications to your home or vehicle may also be covered if medically necessary due to severe injuries.
It's crucial to review your specific insurance policy documents to understand the exact scope and limitations of your PIP coverage, as these can differ even within the same state based on the options you chose. Understanding these benefits is key to processing Common Car Accident Injuries: Complete Guide (2027) without financial strain.
How PIP Limits and Deductibles Work
Like all insurance, PIP comes with specific limits and often a deductible.
- Policy Limits: Each PIP policy will have a maximum dollar amount it will pay out for all covered benefits resulting from a single accident. For example, you might have a $10,000 PIP limit. This means that the total combination of your medical bills, lost wages, and other covered expenses cannot exceed $10,000 from your PIP. If your expenses go beyond this, and you haven't met the tort threshold, you would be personally responsible for the remainder unless you have other health insurance or another avenue for recovery.
- Deductibles: Some states and policies allow for a PIP deductible. This is the amount you must pay out-of-pocket before your PIP coverage begins to pay. For example, if you have a $1,000 PIP deductible and accrue $5,000 in medical bills, you would pay the first $1,000, and your PIP would cover the remaining $4,000. Choosing a higher deductible often lowers your premium but means more out-of-pocket expense in case of an accident.
It's important to understand these limits and deductibles when selecting your policy. While a higher deductible can save you money monthly, it could mean a larger initial financial burden after an accident.
Stacking PIP Coverage and Coordination of Benefits
The concepts of "stacking" and "coordination of benefits" can affect how your PIP coverage interacts with other insurance policies you might have.
- Stacking PIP: In some states, if you own multiple vehicles insured with PIP, you might be able to "stack" your PIP coverage. This means if you have $10,000 PIP on two cars, you might effectively have $20,000 available for your injuries in a single accident, even if you were only in one of the insured vehicles. This depends entirely on state law and your specific policy language.
- Coordination of Benefits: This refers to how your PIP coverage interacts with your health insurance. In many no-fault states, you can choose how your PIP coordinates with your health insurance policy. You might select PIP as your primary payer, meaning it pays first until its limits are exhausted, and then your health insurance kicks in. Alternatively, you might choose to make your health insurance primary, which could reduce your PIP premium but means your health insurance would cover accident-related medical bills first, possibly subject to its own deductibles and co-pays. Each option has financial implications, and it's wise to consider your existing health insurance coverage and financial situation when making this choice.
Understanding these details can be complex, and it’s a good idea to speak with an insurance agent to ensure you have the best coverage for your needs and to understand how these elements would play out if you were involved in a crash.
Important Considerations and Common Misconceptions
No-fault insurance, while designed to simplify some aspects of accident claims, is often misunderstood. Clarifying these common misconceptions is essential for anyone driving or residing in a no-fault state.
No-Fault Does Not Mean No Responsibility
This is perhaps the biggest misconception. Just because your state has a no-fault system for injury claims doesn't mean that fault is completely irrelevant or that nobody is held accountable for causing an accident. Fault still matters significantly in several key areas:
- Property Damage: As mentioned earlier, property damage claims almost always operate under at-fault rules. If someone hits your car, their property damage liability insurance is responsible for paying for the repairs to your vehicle.
- Insurance Premiums: If you cause an accident, your insurance company will almost certainly raise your premiums, regardless of whether your state is no-fault or at-fault. Your driving record directly impacts your rates.
- Serious Injuries: If your injuries meet your state's "tort threshold," you can still sue the at-fault driver for damages like pain and suffering. At this point, proving who was at fault becomes absolutely critical to your ability to recover these additional damages.
- Criminal Charges: If an accident involves reckless driving, drunk driving, or other egregious behavior, the at-fault driver can still face criminal charges, regardless of the no-fault insurance system. This is completely separate from civil claims.
- Traffic Violations: The police officer at the scene will still issue traffic citations to the driver(s) who violated traffic laws, like running a red light or speeding. These citations directly assign responsibility for the actions that led to the crash. For more context, see Who Is at Fault in a Car Accident? Complete Guide (2027).
So, while no-fault alters the initial claim process for personal injuries, it certainly doesn't give negligent drivers a free pass.
The Impact on Your Insurance Premiums
The structure of no-fault laws can have a noticeable impact on insurance premiums. On one hand, the intent of reducing lawsuits for minor injuries was to potentially lower costs. However, the mandatory nature and sometimes extensive coverage requirements of PIP can push premiums up.
In states like Michigan, which historically had some of the most comprehensive (and expensive) no-fault PIP benefits, policyholders often paid significantly more for auto insurance than in at-fault states. Recent reforms in Michigan have aimed to bring down these costs by offering different levels of PIP coverage, but the underlying principle remains: the cost of providing broad, immediate benefits to everyone, regardless of fault, must be covered by premiums.
Furthermore, your personal driving history and claim record still heavily influence your rates. If you're involved in multiple accidents, especially if you're determined to be at fault, your premiums will likely increase significantly, even in a no-fault state. The insurance companies still track fault to assess risk and price policies accordingly.
Uninsured and Underinsured Motorist Coverage in No-Fault States
Uninsured Motorist (UM) and Underinsured Motorist (UIM) coverages are vital, even in no-fault states, and understanding how they interact with PIP is important.
- Uninsured Motorist (UM): This coverage protects you if you're hit by a driver who doesn't have insurance. In an at-fault state, UM coverage would pay for your bodily injuries (and often property damage) that the uninsured driver is responsible for. In a no-fault state, your PIP would first cover your medical expenses and lost wages up to its limits. However, if your injuries meet the state's threshold and your damages (like pain and suffering or medical bills exceeding PIP limits) are greater than what your PIP provides, your UM coverage can then step in to cover these additional losses that the uninsured at-fault driver would have been liable for.
- Underinsured Motorist (UIM): This coverage protects you if the at-fault driver has insurance, but their policy limits aren't enough to cover your total damages. Similar to UM, in a no-fault state, after your PIP has paid its maximum, if your injuries meet the threshold and your total damages exceed the at-fault driver's liability limits, your UIM coverage can provide additional compensation up to your UIM policy limits.
So, while PIP is your first line of defense, UM/UIM remains crucial for protecting you against negligent drivers who lack sufficient insurance, especially when your injuries are severe enough to meet your state's tort threshold. These coverages ensure that even when Fault in an Uninsured Motorist Accident or an underinsured one occurs, you still have avenues for full recovery.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.